
Blogs
PW Consulting: Worldwide Textile Staples Market Forecast to Grow 5.01% CAGR Through 2032
By pmarketresearch, 2026-09-17
Navigating Volatility and Value: Strategic Intelligence for the Global Textile Staples Market (2026-2032)
The global textile staples market stands at a critical inflection point. As stakeholders navigate the period from 2026 to 2032, the interplay between shifting raw material costs, sustainability mandates, and evolving demand structures requires more than surface-level observation. It demands precise, forward-looking intelligence capable of informing capacity allocation, sourcing strategies, and competitive positioning. Our newly released Worldwide Textile Staples Market research report has been engineered specifically for this purpose, translating a decade of historical performance and multi-year forecasts into actionable strategic guidance for executives, investors, and supply chain leaders.
A Market Defined by Scale, Resilience, and Structural Transition
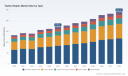
Drawing on a robust analytical framework covering the historical window of 2020 through 2025 and projecting forward to 2032, the report situates the textile staples industry within a trajectory of steady, compound growth. The sector, valued across its core revenue streams, has demonstrated remarkable resilience through cyclical demand fluctuations, supply chain disruptions, and macroeconomic uncertainty. Over the historical tracking period, total market revenue has progressed from approximately 132.45 billion USD in 2020 through a series of demand-driven and supply-constrained phases, reaching an estimated 170.16 billion USD by 2025. Forward projections indicate continued expansion, climbing to 177.04 billion USD in 2026 and advancing toward a projected 239.43 billion USD by 2032, underpinned by a forecasted compound annual growth rate of 5.01 percent.
These figures are not merely historical artifacts; they reflect the compounding effects of population-driven consumption, industrial textile integration, and the gradual maturation of regional manufacturing ecosystems. Yet the headline trajectory masks significant heterogeneity. Growth is neither uniform across product families nor evenly distributed geographically, and the report deliberately deconstructs these layers to reveal where structural advantages emerge and where margin compression risks intensify. Every forecast interval and baseline assumption is stress-tested against upstream feedstock dynamics, downstream end-use adoption curves, and policy-driven demand shifts.
What the Report Delivers: Operational Intelligence Beyond Top-Line Projections
The research is structured to move decisively beyond static sizing. It serves as a working toolkit for strategic planning, providing operational granularity where it matters most. Readers will encounter a comprehensive architecture of analysis that includes:
- A detailed segmentation mapping that isolates performance drivers across major staple fiber categories, application verticals, and regional supply-demand balances, enabling targeted market-entry and portfolio-allocation decisions
- Demand elasticity assessments that link textile staple consumption to downstream apparel, home furnishing, technical textile, and automotive-industrial cycles, highlighting inflection points where substitution patterns, premiumization trends, or specification upgrades alter volume trajectories
- Supply-side capacity and feedstock mapping that traces how upstream chemical intermediates, conversion economics, and regional production footprints influence short-term pricing behavior and long-term cost structures
- Competitive positioning frameworks that evaluate market share distribution, functional differentiation, and vertical integration strategies among leading global and regional producers
- Scenario-based forecasting modules that model how shifts in raw material pricing, sustainability regulation, trade flow reconfiguration, and technological adoption could reshape revenue streams and operating margins across the forecast horizon
Each analytical section is anchored in verifiable commercial realities and designed to be immediately usable in boardroom discussions, capital allocation reviews, and sourcing strategy workshops. The report does not simply describe the market; it equips decision-makers with the connective tissue between macro trends and tactical execution.
Competitive Architecture and the Emerging Battleground for Differentiation
The global textile staples landscape is shaped by a blend of integrated petrochemical giants, specialized fiber innovators, and regionally dominant manufacturers. The report provides an in-depth competitive profiling of the companies that are actively defining market standards, price signaling behavior, and technological baselines.
Indorama Ventures Public Company Limited, headquartered in Bangkok, Thailand, continues to operate as a major global producer of polyester staple fiber, spanning both virgin and recycled grades. Its significant capacity base across Asia and integrated operations position it as a central supplier to apparel, home textile, and nonwoven markets, while its strategic emphasis on recycled polyester staple fibers reflects a broader industry pivot toward circularity. Reliance Industries Limited, based in Mumbai, India, stands as a leading integrated polyester staple fiber producer with large-scale manufacturing operations that supply both virgin and recycled PSF for apparel and industrial applications, leveraging scale and domestic demand strength.
Toray Industries Inc., operating from Tokyo, Japan, brings a specialty orientation to the market, offering polyester staple fibers and other synthetic staples engineered for high-performance applications in apparel, automotive, and filtration textiles. Lenzing AG, headquartered in Lenzing, Austria, occupies a distinct premium niche as a premier producer of cellulosic viscose staple fibers derived from sustainable wood pulp, serving high-value apparel and nonwoven segments where brand equity and environmental credentials matter significantly. Grasim Industries Limited, part of the Aditya Birla Group and based in Mumbai, India, remains a key manufacturer of viscose staple fiber, with major production facilities supplying global blended yarn and fabric markets.
Alpek S.A.B. de C.V., headquartered in Monterrey, Mexico, produces polyester staple fiber through integrated PTA/PET operations, serving North American and international textile staple markets with a competitive cost and logistics advantage. Far Eastern New Century (FENC), based in Taipei, Taiwan, operates as a significant Asian producer of polyester staple fibers, including recycled grades, supplying apparel and home textile applications. Teijin Frontier Co., Ltd., also headquartered in Tokyo, Japan, supplies specialty synthetic staple fibers, including polyester, for technical textiles, automotive, and performance apparel. W. Barnet GmbH & Co. KG, based in Aachen, Germany, specializes in polyester and other synthetic staple fibers for nonwovens and technical textile applications, emphasizing functional performance. Sinopec Yizheng Chemical Fibre Company, located in Yizheng, China, operates as a large-scale producer of polyester and viscose staple fibers integrated with upstream petrochemical operations, linking feedstock economics directly to staple fiber output. Huvis Corporation, headquartered in Seoul, South Korea, manufactures polyester staple fibers for a broad range of textile staple end-uses, including filling and apparel.
Sewing Threads Market
This competitive mosaic is not static. The report evaluates how scale economics, product specialization, sustainability positioning, and regional integration create divergent strategic options. It further examines how these players interact within a market structure where the top three competitors collectively account for an estimated 18.4 percent of total revenue and the top five capture approximately 26.15 percent, indicating a moderately distributed landscape with room for both consolidation and niche differentiation.
2026 Industry Dynamics: Pricing Signals, Capacity Movements, and Regulation
The current operating environment is characterized by a series of interlinked developments that directly affect sourcing decisions, inventory planning, and capacity investment timing. Raw material pricing has emerged as a central variable. In China, polyester staple fiber prices have trended upward, supported by favorable upstream cost factors. More specifically, the domestic average market price for polyester staple fiber of standard specifications reached approximately 8,160 RMB per ton by mid-to-late March 2026, reflecting a notable intra-month increase driven by upstream PTA cost surges. Parallel movements have been observed in key feedstock markets, where PTA and MEG prices in India experienced sharp fluctuations in March 2026, rising before partially correcting. These upstream swings have direct pass-through implications for staple fiber margins and regional price competitiveness.
Viscose staple fiber markets have exhibited their own supply-driven dynamics. February 2026 pricing data recorded China-based viscose staple fibre prices at approximately 1,848 USD per metric ton and Indian prices at roughly 1,941 USD per metric ton, influenced by tight supply conditions and low inventories. These snapshots illustrate how regional supply tightness, inventory positioning, and mill operating rates can create short-term pricing divergence even within a broadly integrated global market. The report contextualizes these signals within longer-term cost curves, helping buyers and producers distinguish transient volatility from structural price shifts.
Capacity and product strategy developments further illustrate how participants are repositioning for the next cycle. In February 2026, Aksa Akrilik Kimya Sanayii A.S. commissioned an expanded production line, adding 30,000 metric tons of annual acrylic staple fiber capacity with advanced solvent recovery and energy efficiency upgrades tailored for technical textiles. Earlier, in January 2026, Pasupati Acrylon Limited announced capacity expansion at its Samba manufacturing facility in India, targeting increased acrylic staple fiber supply to domestic yarn spinning and knitwear clusters. On the product innovation side, Teijin Frontier Co., Ltd. launched THERMOFRONT in October 2025, a new master brand for sheet insulation that combines environmental responsibility with high thermal performance using specialty staple fibers. Indorama Ventures Public Company Limited expanded its dejaTM fiber and filament yarn portfolio in May 2025, enhancing sustainability offerings in recycled polyester staple fibers. Together, these moves highlight a market where capacity additions are increasingly linked to technical specifications, recycling credentials, and energy-efficient process design rather than volume alone.
Worldwide Textile Staples Market
Regulatory and sustainability pressures continue to reshape end-use preferences and technology adoption. In North America and Europe, sustainability mandates are favoring closed-loop and low-emission viscose staple fiber technologies amid broader textile environmental regulations. The report examines how these mandates influence procurement specifications, accelerate substitution toward certified cellulosic and recycled fibers, and reshape competitive advantages for manufacturers with advanced process capabilities and traceability systems.
Strategic Imperatives for 2026 Decision-Making
Translating these dynamics into executable strategy requires a clear understanding of where value is being created and where risk is accumulating. The report is designed to support several core strategic functions:
- Portfolio and sourcing alignment: Identifying which staple fiber categories and regional supply bases offer the most resilient cost profiles and specification flexibility under current feedstock and inventory conditions
- Capacity and investment timing: Evaluating how recent capacity expansions and product launches alter regional supply balances, and determining where new investment or partnership opportunities may emerge over the forecast period
- Competitive positioning: Understanding how leading players leverage vertical integration, specialty formulations, and sustainability credentials to protect margins and capture premium segments, and where fragmented segments remain open to focused entrants
- Regulatory and sustainability readiness: Mapping how evolving environmental mandates and consumer expectations influence demand for closed-loop, low-emission, and recycled staple fibers, and preparing procurement and product development roadmaps accordingly
By integrating historical performance, forward-looking projections, competitive profiling, and real-time market signals, the analysis enables organizations to convert uncertainty into structured decision-making. The goal is not to predict every fluctuation, but to establish a reliable framework for responding to them with discipline and speed.
Access the Complete Intelligence
The Worldwide Textile Staples Market research report offers a comprehensive, evidence-based view of the market's trajectory from 2026 through 2032, combining rigorous segmentation analysis, competitive dynamics, and scenario-ready forecasting into a single strategic asset. To explore the full dataset, regional breakdowns, application-level demand insights, and detailed company profiles that underpin the analysis presented here, please visit the source webpage to access the complete report. The publication is designed to serve as a foundational reference for procurement leaders, corporate strategists, investors, and industry analysts seeking to navigate the next phase of global textile staples market evolution with confidence and precision.
For detailed analysis of this topic, please visit the official page: Worldwide Textile Staples Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Pool & Spa Supplies Market Hits $18.45B in 2025, 5.24% CAGR to 2032
By pmarketresearch, 2026-09-17
Navigating the Currents: Strategic Intelligence for the Global Pool and Spa Supplies Market 2026
The global pool and spa supplies industry stands at a critical inflection point as it moves through the 2026 calendar year. For executives, investors, and strategic planners, the difference between reactive management and proactive growth lies in the quality of intelligence available. Our latest Worldwide Pool and Spa Supplies Market research report is designed not merely as a data repository, but as a strategic compass for navigating the complex economic, regulatory, and competitive currents defining this sector. As the market continues to expand beyond its 2025 baseline of 18.45 billion USD, understanding the trajectory toward 2032 becomes essential for capital allocation, supply chain optimization, and product portfolio strategy.
This comprehensive analysis synthesizes historical performance data from 2020 through 2025 with forward-looking projections extending to 2032. The narrative that emerges is one of sustained growth tempered by significant macroeconomic headwinds. With a projected compound annual growth rate of 5.24 percent over the forecast period, the sector demonstrates resilience, yet the path to 26.38 billion USD by 2032 is not linear. Stakeholders must understand where value is consolidating, how regulatory shifts are reshaping cost structures, and which competitive maneuvers are defining market leadership in this mature yet evolving landscape.
Market Trajectory and Macro Economic Context
The historical window from 2020 to 2025 established a robust foundation for the industry. Revenue grew from 14.35 billion USD to 18.45 billion USD, reflecting a post-pandemic surge in residential outdoor living and a gradual stabilization of commercial hospitality sectors. The transition from 2025 into the forecast period suggests a continued upward momentum, with 2026 opening at 18.88 billion USD. However, market participants must recognize that aggregate top-line figures mask underlying volatility driven by input costs, tariff regimes, and shifting consumer spending patterns.
Worldwide Pool and Spa Supplies Market
Our forecast model projects the market will reach approximately 20.61 billion USD by 2027 and 21.32 billion USD by 2028, before accelerating toward 23.51 billion USD in 2029. It is crucial for decision-makers to note that growth trajectories are subject to external pressures. The market demonstrates a nuanced path, with slight consolidations observed in certain forecast years before resuming expansion toward the 26.05 billion USD mark in 2031 and the final 2032 projection. This volatility underscores the necessity of scenario planning rather than reliance on static growth assumptions.
Key macro drivers influencing this trajectory include the enduring preference for residential leisure assets and the ongoing rehabilitation of commercial aquatic facilities. However, the cost environment has shifted materially. Industry estimates suggest the U.S. pool service and maintenance segment alone reached 7.2 billion USD in 2025, with residential pool owners averaging around 1,700 USD in annual maintenance spend. This recurring expenditure supports a steady baseline demand for chemicals and maintenance tools, buffering the market against some volatility in equipment sales.
Regulatory Headwinds and Supply Chain Dynamics
No strategic assessment of the 2026 landscape is complete without addressing the profound impact of trade policy and raw material costs. The expansion of Section 232 tariffs in the United States during 2025 has subjected steel and aluminum content in derivative products to significant duties, reaching up to 50 percent for certain equipment categories including pumps, valves, and fittings. These measures, combined with reciprocal tariffs impacting imports from key trading partners, have fundamentally altered the cost calculus for manufacturers and distributors.
Further compounding these pressures, new tariffs on imported steel and aluminum at a 25 percent rate, alongside baseline duties on certain chemicals and components from China, are driving up manufacturing input costs. For domestic chlorine and pool chemical manufacturers reliant on imported inputs, these cost increases pose a direct threat to margins and retail pricing stability heading into the peak 2025-2026 pool season. The Pool and Hot Tub Alliance continues to advocate on these policy fronts, representing a broader 62 billion USD U.S. industry ecosystem, but the immediate operational reality for businesses is one of compressed margins and necessary price adjustments.
Pool Chemical Market
Strategic implications of these dynamics are multifaceted. Companies must evaluate their supplier diversification strategies, reconsider inventory positioning ahead of tariff implementations, and assess the elasticity of their customer base regarding price increases. Our report dissects these supply chain vulnerabilities to help organizations model the financial impact of continued regulatory friction and identify opportunities for localization or value engineering that can mitigate cost exposure.
Segmentation Landscape: Where Value Is Created
Understanding the architecture of the market is vital for targeting investment and sales efforts. The industry is broadly structured around equipment, consumables, and accessories, each exhibiting distinct growth profiles and sensitivity to economic cycles. In the equipment category, which represents a substantial portion of market revenue, innovation in energy efficiency and automation is driving replacement cycles. Water chemicals and treatment solutions form the recurring revenue backbone, closely tied to the aforementioned maintenance spend trends and regulatory standards around water quality and safety.
Maintenance tools and accessories, along with advanced cleaning systems, represent high-growth niches fueled by labor shortages in the service sector and consumer demand for convenience. The rise of robotic solutions and smart monitoring technologies is reshaping how owners interact with their aquatic assets, shifting value from purely mechanical components to integrated technology ecosystems. These segments are not growing in isolation; they are increasingly interdependent, with automation systems requiring compatible equipment and specific chemical regimes to function optimally.
Geographically, the market exhibits diverse maturity levels and growth potentials. North America remains a dominant revenue contributor, reflecting high pool penetration rates and a strong culture of residential outdoor living. Europe follows as a significant market, driven by tourism infrastructure and regulated public health standards. The Asia Pacific region presents a different dynamic, characterized by rapid urbanization and increasing disposable incomes fueling new installations. Latin America and the Middle East and Africa, while smaller in current revenue contribution, offer emerging opportunities tied to hospitality development and climate-specific demand. Our analysis provides the qualitative context and relative positioning needed to prioritize these regions without relying solely on historical volume metrics.
Competitive Arena: Strategic Positioning of Key Players
The competitive landscape is characterized by a mix of global equipment manufacturers, specialized technology providers, and massive distribution networks. Market concentration data indicates that the top three players hold approximately 32.4 percent of the market, while the top five control around 44.8 percent. This level of concentration suggests a competitive environment where scale advantages in distribution and manufacturing are significant, yet ample room remains for specialized innovators and regional leaders to capture value through differentiation.
Pentair plc continues to assert its position as a global leader, leveraging a comprehensive portfolio spanning pumps, filters, heaters, automation, and water treatment solutions across both residential and commercial segments. Their ability to integrate hardware with software services positions them well in a market increasingly driven by efficiency and connectivity. Similarly, Fluidra S.A. has built a formidable brand portfolio including Zodiac, Jandy, AstralPool, and Polaris, addressing everything from cleaning and filtration to heating and chemical systems. Their strategy emphasizes brand segmentation to address varied price points and consumer preferences across different geographies.
Hayward Holdings, Inc. remains a major force in the North American market, offering a wide array of equipment including pumps, filters, heaters, cleaners, lighting, and automation controls. Their focus on reliability and broad dealer networks reinforces their standing in the replacement and service markets. Maytronics Ltd. has carved a specialized niche through its Dolphin brand of robotic pool cleaners, capitalizing on the shift toward automated maintenance solutions that reduce labor dependency. This focus on high-value accessories allows them to punch above their weight in terms of margin contribution relative to volume.
In the residential infrastructure space, Latham Group, Inc. stands as the largest designer and manufacturer of in-ground residential pools, offering fiberglass pools, vinyl liners, and safety covers. Their recent milestone markings and product launches, including new plunge pools with integrated spas and partnerships in artistic swimming, signal a strategy of brand elevation and diversification into lifestyle experiences. Pool Corporation operates on the other side of the value chain as the largest wholesale distributor globally, wielding immense influence over product availability and pricing dynamics through its extensive sales centers and exclusive partnerships. Their recent showcases of new chemical systems and filter technologies highlight the importance of distribution partners in bringing innovation to market quickly.
Other notable participants include Jacuzzi Brands LLC with their premium positioning in spas and water features, Waterco Ltd. in filtration and treatment, and a growing cohort of manufacturers from China such as Emaux Water Technology and Guangdong Laswim, who are expanding their global footprint through cost-competitive equipment and accessories. Companies like Aqua Products Inc., S.R. Smith, Waterway Plastics, Speck Pumps, and Intex Recreation Corp. further diversify the landscape, addressing specific niches from robotic cleaners to above-ground solutions and specialized plumbing components. The interplay between these players defines pricing power, innovation speed, and channel access across the industry.
Innovation and Event Dynamics Shaping 2026
The flow of innovation in this sector is accelerated by trade shows and industry gatherings that serve as barometers for technological and market trends. The International Pool Spa Patio Expo in late 2025 demonstrated the industry's commitment to sustainability and product diversity, featuring participation from 40 countries and innovations across over 100 categories. Highlights included advancements in robotic cleaners, filtration efficiency, automation interfaces, and sustainability initiatives designed to support the 2026 buying cycle. Such events underscore the industry's pivot toward solutions that address energy consumption, water conservation, and operational ease.
Corporate activity in early 2026 further illustrates the dynamic nature of the market. Latham Group's recent activities, including the introduction of new deluxe plunge pools and strategic partnerships, reflect a focus on premiumization and brand visibility. Concurrently, Pool Corporation's retail summit showcased new chemical systems and exclusive partnerships with innovative solution providers, signaling a distributor-led push toward differentiated service offerings and proprietary product lines. These developments suggest that competitive advantage in 2026 will increasingly derive from the ability to bundle equipment with consumables, offer service-integrated solutions, and leverage exclusive channels to capture customer loyalty.
Strategic Imperatives for Decision Makers
As organizations prepare their strategies for the remainder of 2026 and beyond, several imperatives emerge from the current market intelligence. First, supply chain resilience must be prioritized. The tariff environment requires a rigorous review of sourcing strategies, with potential benefits to be gained from regionalizing production or securing long-term contracts that hedge against input cost volatility. Second, product portfolios should be evaluated through the lens of total cost of ownership for the end customer. As energy and water costs rise, solutions that deliver operational savings will command premium positioning and drive adoption.
Third, the recurring revenue potential in chemicals and maintenance tools should not be underestimated. With residential owners spending significantly on annual maintenance, businesses that can capture this recurring stream through subscription models, smart dosing systems, or service partnerships will build more predictable revenue bases. Fourth, competitive positioning requires clarity on where to compete. The market concentration data suggests that while leaders hold significant share, there are viable paths for specialists, particularly in high-growth segments like robotic cleaning and automation. Finally, geographic strategy must be nuanced. Growth rates and regulatory environments vary widely, and a one-size-fits-all approach risks misallocation of resources.
Conclusion: The Value of Deep Intelligence
The Worldwide Pool and Spa Supplies Market is evolving under a complex set of forces that demand more than superficial analysis. From the impact of trade policies on manufacturing costs to the shifting preferences of residential consumers and the strategic maneuvers of key competitors, the variables influencing success are numerous and interdependent. Our report provides the depth, granularity, and forward-looking perspective required to navigate this environment with confidence.
By accessing the full research, stakeholders will gain access to detailed segmentation analysis, precise regional forecasts, competitive benchmarking, and scenario models that quantify the impact of regulatory and economic variables. The insights contained within are designed to support critical decisions regarding market entry, product development, M&A targeting, and capacity planning. In a market projected to exceed 26 billion USD by 2032, the cost of incomplete intelligence is far greater than the investment in comprehensive analysis.
We invite you to explore the full report to unlock the specific data points, strategic frameworks, and actionable recommendations that will empower your organization to thrive in the dynamic world of pool and spa supplies. The currents are strong, but with the right intelligence, your strategy can not only withstand them but harness them for sustained growth.
For detailed analysis of this topic, please visit the official page: Worldwide Pool and Spa Supplies Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Military Grade Computer Market Hits $10.5B in 2025, Heading to $16.26B by 2032
By pmarketresearch, 2026-09-17
Global Resilience: Strategic Imperatives in the Worldwide Military Grade Computer Market (2026-2032)
The defense technology landscape has entered a decisive phase. As geopolitical tensions reshape procurement priorities and operational theaters demand greater computational sovereignty, the Worldwide Military Grade Computer Market stands at a critical inflection point. For executives navigating procurement, R&D allocation, and supply chain resilience, understanding the trajectory of this sector is no longer optional—it is foundational to strategic readiness.
Based on our latest comprehensive analysis, the market is projected to expand from a base of approximately $10,500 million in 2025 to $16,263.31 million by 2032, reflecting a compound annual growth rate of 6.45%. This growth is not merely a function of increased defense spending; it represents a structural transformation in how militaries compute, process data, and maintain operational continuity under extreme conditions. Our freshly released Worldwide Military Grade Computer Market report dissects this evolution with granular precision, offering decision-makers a roadmap through a sector where mission assurance and technological agility must coexist.
A Market Anchored in Operational Necessity
Military-grade computing differs fundamentally from commercial IT markets. Where enterprise buyers optimize for cost and convenience, defense procurement prioritizes survivability, interoperability, and compliance with rigorous environmental and electromagnetic standards. The market's trajectory reflects a dual engine: modernization of legacy platforms and deployment of next-generation capabilities across ground, airborne, and naval domains.
Between 2020 and 2025, cumulative expansion demonstrated resilience even amid supply chain disruptions and component scarcity. In 2020, the market stood at $7,681.76 million; by 2025, that figure reached $10,500.0 million. The forecast period ahead compounds this momentum, with annual valuations climbing steadily toward 2032. This sustained trajectory signals that defense organizations are treating rugged computing not as a tactical utility but as a strategic asset class—one that directly enables command, control, communications, computers, intelligence, surveillance, and reconnaissance (C4ISR) functions across contested environments.
Yet raw valuation figures only tell the opening chapter. The substance of this market lies in how spending is distributed across form factors, platforms, and geographies, and how competitive dynamics are being reshaped by technological standards, regulatory frameworks, and raw material availability. Our report provides the full map; what follows is a strategic preview of the terrain.
Segmentation Dynamics: Where Value Concentrates
The military computing ecosystem bifurcates across three analytical dimensions—type, platform, and region—each carrying distinct investment and risk implications. In terms of product architecture, embedded systems and rugged mobile platforms represent the dominant expenditure categories, reflecting a shift toward distributed, edge-capable hardware that can operate independently of stable infrastructure. Servers and storage units, while smaller in absolute terms, are gaining strategic relevance as data-intensive battlefield architectures demand localized processing for latency-sensitive decision loops. Wearable and handheld computers further illustrate how soldier-system digitization is pushing computing intelligence into the tactical edge.
Platform-wise, ground-based systems currently command the largest share of compute investment, supported by the breadth of land-vehicle modernization programs worldwide. Airborne applications follow closely, driven by avionics upgrades, unmanned aerial system payloads, and cockpit digitization initiatives that demand SWaP-optimized rugged hardware. Naval platforms round out the triad, where corrosive marine environments and electromagnetic compatibility requirements impose particularly stringent qualification barriers.
Geographically, the market displays pronounced concentration patterns. North America remains the most mature and investment-dense region, underpinned by sustained U.S. procurement cycles and export opportunities. Asia Pacific exhibits the strongest growth momentum, reflecting regional security reassessments and indigenous platform development. Europe maintains a stable, capability-focused demand profile, while Middle East & Africa and Latin America represent smaller but strategically significant deployments tied to specific modernization programs and allied cooperation frameworks.
Crucially, these segmentation dynamics are not static. They are being recalibrated by procurement policies, interoperability mandates, and supply chain constraints that differ dramatically across regions. The complete segmentation architecture—including revenue allocations, growth rate differentials, and sub-segment crossover effects—is mapped in detail within the report, where clients can identify which nodes of the value chain offer the highest strategic leverage for their specific business posture.
Competitive Architecture: Specialists, Integrators, and the Premium Tier
The competitive field in military-grade computing is characterized by a blend of incumbent defense electronics integrators, specialized rugged hardware manufacturers, and cross-over commercial entities that have adapted their platforms to defense specifications. Market concentration metrics indicate a moderately consolidated landscape, with the top three players holding approximately 34.2% of total market revenue and the top five accounting for roughly 51.85%. This structure suggests room for both established leaders and agile entrants who can meet qualification thresholds and deliver differentiated performance in harsh environments.
Several organizations define the sector's competitive contours. Curtiss-Wright Corporation exemplifies the mission-computer modernization playbook, with recent contract awards focused on MOSA-aligned computing architectures and platform upgrades for aircraft such as the U.S. Air Force C-17. Leonardo DRS has built a formidable position as a premier supplier of rugged military computer systems and displays, with sole-source battle management responsibilities and a portfolio exceeding 200,000 battle-proven systems qualified to military standards. General Dynamics and Northrop Grumman extend the integrator dimension, embedding rugged computing within broader mission systems and defense electronics portfolios for ground, naval, and airborne applications.
Private and multinational specialists further diversify the ecosystem. Getac Technology Corporation leverages MIL-STD-810H certified rugged platforms and COTS-aligned customization to serve defense applications in extreme conditions. Panasonic's Toughbook line brings commercial-hardened portability into field operations meeting military durability standards. Crystal Group, Mercury Systems, Kontron, and Extreme Engineering Solutions address embedded, VPX, and COM Express requirements, each emphasizing secure, size-weight-and-power-optimized architectures for mission-critical applications. MilDef Group, Neousys Technology, RuggON, and VarTech Systems contribute certified rugged computers and displays tuned to environmental and electromagnetic demands, while Wolf Advanced Technology, Acura Embedded Systems, Core Systems, and BAE Systems broaden the geographic and application footprint of rugged computing solutions across command, control, and connectivity environments. Elbit Systems Ltd. rounds out this cohort with integrated rugged computing and C4ISR offerings.
Recent developments underscore how product launches and program wins continuously reshape battlefield relevance. In March 2026, VersaLogic Corporation introduced the Raptor, an ultra-compact rugged embedded computer utilizing 13th Generation Intel processors designed for defense, edge, and uncrewed systems. The same month, Curtiss-Wright secured the selection to modernize U.S. Air Force C-17 mission computing with MOSA-aligned mission computers. In November 2025, Getac highlighted customized rugged military computer solutions in alignment with U.S. DoD COTS directions and MIL-STD-810H standards. These events are not isolated; they are indicators of the pace and precision with which competitive advantage is being contested.
The full competitive analysis in our report includes organizational profiles, strategic positioning, capability emphasis, and recent activity tracking across the key company set, enabling clients to benchmark partnership potential, competitive threats, and white-space opportunities with greater confidence.
Technology, Standards, and Regulatory Gravity
Military-grade computers do not succeed on performance alone. Qualification, certification, and regulatory compliance form the invisible scaffolding of this market. MIL-STD-810H remains the active standard for environmental testing, governing how rugged systems endure vibration, shock, temperature extremes, humidity, and particulate intrusion. Compliance with this standard, alongside electromagnetic compatibility requirements and platform-specific qualification processes, dictates not only product design but also time-to-field and qualification cost.
Parallel to technical standards, regulatory frameworks exert substantial influence over market behavior. The U.S. Department of Defense maintains ITAR and export control frameworks under 22 CFR Part 124 for defense services and technical data related to military computing systems. These controls shape global supply networks, partnership models, and cross-border technology transfer. They also create differentiated market access pathways, where companies with robust compliance infrastructure and secure manufacturing footprints enjoy structural advantages.
Supply-side risks add another layer of complexity. Recent years have highlighted the vulnerability of defense electronics to critical mineral and semiconductor-grade material disruptions. China's imposition of export controls and bans on gallium, germanium, and antimony—materials integral to semiconductors and defense electronics—has rippled through supply chains. The United States remains 100% import-reliant on gallium and approximately 85% reliant on antimony, with critical mineral shortages threatening defense production capacity for electronics including military computers. Rare earth elements face even broader concentration risks, with China dominating more than 90% of global processed rare earths used in military computing components. These realities are pushing procurement organizations and manufacturers alike toward diversification, stockpiling strategies, and qualification of alternative material pathways.
For companies operating in this space, regulatory and supply chain fluency is as important as engineering excellence. The report integrates these dynamics into market projections and competitive interpretation, helping clients anticipate how standards, controls, and raw material availability will shape pricing, lead times, and regional accessibility over the 2026-2032 horizon.
Strategic Reading for the 2026 Decision Cycle
As organizations finalize multi-year investment plans, three priorities emerge from the market's current trajectory:
- Platform modernization is cumulative, not cyclical. Mission computing refresh cycles span years, and programs winning today's milestones will influence demand well beyond the forecast window. Decision-makers should evaluate where their offerings align with active modernization campaigns across air, land, and sea domains.
- Certification is a moat, not a checkbox. MIL-STD compliance, ITAR readiness, and SWaP optimization are table stakes for credibility. Yet the differentiation point increasingly lies in how quickly and reliably these attributes can be demonstrated across product families and customization requests.
- Supply chain resilience has become a procurement criterion. With critical mineral concentration and export controls affecting component availability, buyers are factoring supplier geographic diversification, stock strategies, and alternative-material roadmaps into sourcing decisions. Companies that can articulate and deliver resilience will capture disproportionate influence in qualified vendor lists.
These themes are explored across every section of the report, from market sizing and segmentation to competitive profiling and regulatory context. The objective is not to present a static snapshot but to equip leadership teams with a decision-grade intelligence framework for 2026 and the years ahead.
Worldwide Military Grade Computer Market
Inside the Report: What Decision-Makers Will Gain
Our Worldwide Military Grade Computer Market study is structured to convert complex datasets into actionable strategic insight. Readers will find:
- A full historical and forecast market valuation series, anchored in consistent methodology and expressed in U.S. dollars, enabling revenue planning, benchmarking, and scenario modeling across the 2020-2025 historical window and the 2026-2032 forecast period.
- Detailed segmentation analysis across type, platform, and region, revealing where spending concentrates and how growth velocities differ by category and geography.
- Competitive landscape mapping with company profiles, capability summaries, and recent development tracking, providing a clear view of who is winning programs, launching products, and shaping standards adoption.
- Contextual analysis of regulatory frameworks, qualification standards, and raw material supply dynamics, integrated directly into market interpretation rather than treated as separate appendices.
- Identification of value-chain leverage points, enabling clients to prioritize market-entry pathways, partnership structures, and R&D investments in line with verified demand signals.
The report is intended for executives who require more than directional intuition. It is designed for teams that must justify capital allocation, align product roadmaps with procurement realities, and assess competitor moves against a quantified market baseline.
Access the Full Intelligence
The trajectory of the worldwide military grade computer market is being written now, in program offices, test ranges, and supply chain corridors around the world. To navigate it successfully, organizations need more than high-level estimates; they need precise segmentation, competitive granularity, and the strategic context to interpret change as it happens.
This article has outlined the strategic logic and the macro-scale direction of the market, but the full dataset, segmentation detail, company-level analysis, and scenario-ready forecasting are reserved for clients who engage directly with the complete study. The comprehensive intelligence—built to inform procurement strategy, market entry planning, and competitive positioning throughout 2026 and into 2032—is available through our official research portal.
For a market where mission assurance and technological adaptation determine outcomes, clarity is not a luxury. It is an operational requirement. We invite decision-makers to access the full report and equip their teams with the depth required to act decisively in the years ahead.
Embedded Computer Market
For detailed analysis of this topic, please visit the official page: Worldwide Military Grade Computer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
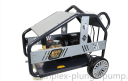
Industrial operations frequently depend on controlled fluid movement for cleaning, processing, water treatment, equipment maintenance, and production support. In these environments, a High Pressure Pump can provide the pressure generation required for applications where standard transfer equipment is insufficient. However, effective equipment selection involves much more than choosing a unit with a high pressure rating. Engineers and purchasing teams need to consider flow demand, operating conditions, fluid properties, duty cycles, installation requirements, and maintenance practices together.
Pressure and flow are closely connected but represent different operating requirements. A system may require substantial pressure while using a relatively controlled flow rate, while another application may prioritize higher fluid volume. Selecting equipment based only on one parameter can create an imbalance between the pump and the rest of the system. A suitable configuration should provide the required operating conditions while leaving an appropriate margin for normal variations in demand.
Pump design is another important consideration. Industrial pressure equipment can use different mechanical configurations depending on the intended application. Piston and plunger arrangements are commonly associated with applications requiring controlled delivery and elevated pressure. The number of pumping elements, stroke characteristics, drive arrangement, and valve configuration can all influence how fluid is delivered through the system. Consequently, a High Pressure Pump should be selected according to the complete operating profile rather than a single specification.
Material compatibility deserves careful attention when the pumped fluid is not ordinary clean water. Industrial liquids may contain chemicals, suspended particles, or other substances that can affect wetted components. Corrosion resistance, mechanical strength, seal compatibility, and temperature tolerance should therefore be considered during system planning. Choosing materials that correspond with actual operating conditions can help reduce premature deterioration and maintenance requirements.
Sealing technology is equally significant because pressure systems depend on effective containment of the working fluid. Seals and packing components are exposed to repeated pressure changes and mechanical movement. Their service life can depend on pressure, temperature, fluid characteristics, surface condition, alignment, and maintenance practices. Regular inspection can help operators identify leakage or abnormal wear at an early stage and take corrective action before a minor issue develops into a larger maintenance problem.
Industrial cleaning represents one of the most recognizable applications for pressure-generation equipment. High-pressure water can assist with removing dirt, residues, deposits, and other contaminants from machinery and industrial surfaces. The cleaning process depends on the relationship between pressure, flow, nozzle geometry, spray distance, water temperature, and the nature of the contamination. Using excessive pressure is not always appropriate because some surfaces or components may require controlled cleaning conditions.
In water treatment environments, pressure equipment may support filtration, flushing, circulation, and other process operations. Stable fluid delivery can be useful when downstream equipment requires predictable flow conditions. System designers may combine pumping equipment with valves, filters, pressure regulators, accumulators, and monitoring devices to create a more controlled process. The complete arrangement should be designed around the characteristics of the treatment process and the required operating range.
Maintenance planning has a direct influence on equipment availability. Operators can establish inspection routines covering lubrication, valves, seals, connections, hoses, pressure indicators, and other relevant components. Changes in operating noise, vibration, temperature, pressure behavior, or leakage may indicate that inspection is necessary. Preventive maintenance does not eliminate every possible failure, but it can provide a structured method for identifying wear and maintaining equipment in suitable operating condition.
Energy consumption should also be considered when designing a pressure system. Inefficient piping, unnecessary pressure losses, poor inlet conditions, and operation far from the intended duty point can increase energy demand. Properly sized piping and suitable system controls may help reduce avoidable losses. Keeping filters clean and maintaining mechanical components in appropriate condition can also contribute to consistent operation.
Installation is often overlooked during equipment selection, even though it can affect practical performance significantly. The pump should be installed on a stable foundation with appropriate alignment and sufficient access for inspection. Inlet piping should avoid unnecessary restrictions, while discharge connections should be arranged to manage pressure safely. Proper installation also makes routine maintenance easier and can support longer service intervals under appropriate operating conditions.
When evaluating pressure equipment for industrial use, organizations can benefit from reviewing application requirements before comparing individual models. Factors such as fluid type, required pressure, expected flow, operating frequency, environmental conditions, maintenance capability, and system configuration can help narrow the available options. A properly matched High Pressure Pump becomes part of a coordinated fluid-handling system rather than an independent component. Businesses seeking additional information about industrial pumping equipment can review https://www.triplex-plungerpump.com/product/pumps/ for product categories and application-oriented pumping solutions.
PW Consulting: Machine-Direction Orientation Films Market Hits $6.37B in 2025, 5.76% CAGR to 2032
By pmarketresearch, 2026-09-17
Strategic Imperatives in the Worldwide Machine-Direction Orientation Films Market: A 2026 Outlook
The global packaging industry is undergoing a structural transformation driven by sustainability mandates, recyclability requirements, and the relentless pursuit of material efficiency. At the heart of this shift lies the machine-direction orientation (MDO) films market, a critical enabler of mono-material flexible packaging solutions that are increasingly mandated by regulatory frameworks and valued by brand owners. For enterprise decision-makers navigating the 2026 landscape, understanding the trajectory, competitive architecture, and value pools of this market is not optional—it is a strategic necessity. This article introduces the key findings and analytical scope of the latest Worldwide Machine-Direction Orientation Films Market study, positioning this intelligence as a foundational tool for capital allocation, supply chain strategy, and competitive positioning through the end of the decade.
From a macroeconomic perspective, the market has demonstrated consistent, compounding growth over the past half-decade. Revenue expanded from approximately $4.85 billion in 2020 to an estimated $6.37 billion in 2025, reflecting a steady upward trajectory that underscores the technology's transition from a niche specialty to a mainstream packaging substrate. The study projects this momentum to continue unabated through the forecast horizon, culminating in a market valuation approaching $9.42 billion by 2032. This expansion is underpinned by a compound annual growth rate of 5.76 percent, a figure that places MDO films in a favorable growth bracket relative to broader commodity polymer markets. For strategy teams, this growth profile signals durable demand drivers rather than cyclical fluctuations, warranting long-term capacity planning and technology investment considerations.
The Strategic Architecture of the Study
A market research report is only as valuable as its actionable granularity. This study is engineered to move beyond top-line sizing and deliver a granular, operation-ready intelligence framework for packaging converters, resin producers, equipment manufacturers, and brand owners. The analytical architecture is built around four interconnected pillars, each designed to translate market dynamics into executable strategic options.
1. Segmentation Dynamics and Value Pool Mapping
The report conducts a comprehensive decomposition of the market across material grades, application verticals, and geographic territories. By isolating consumption patterns, growth velocities, and structural shifts within each segment, the analysis reveals where margin pools are forming and where substitution risks are materializing. For instance, the material spectrum is evaluated across polyethylene, polypropylene, polyester, and polyamide-based substrates, with a focused lens on how mono-material architecture is reshaping share dynamics. Application-level scrutiny spans food and beverage packaging, personal care and hygiene, industrial and labeling uses, and medical and healthcare segments, mapping how regulatory pressure, barrier performance requirements, and conversion economics diverge across these end markets. Geographic dispersion is similarly mapped across Asia Pacific, Europe, North America, Latin America, and the Middle East and Africa, contextualizing capacity footprints, trade flows, and regional regulatory calendars within a unified growth narrative.
High Barrier Mdo Pe Film Market
2. Competitive Landscape and Capability Benchmarking
Understanding who shapes the market—and how—is central to formulating winning strategies. The study profiles the leading participants that define production standards, drive technology diffusion, and influence commercial terms across the value chain. These include Charter Next Generation, RKW Group, Polifilm Extrusion, Trico Specialty Films, Avery Dennison, Coveris, Borealis, Longdapac, Cloud Film, Jiangsu Qianrun New Material Technology, Amcor, NOWOFOL, Lenzing Plastics, Futamura, Toray Industries, and Polysack Plastic Industries, among others. Rather than presenting a static directory, the report evaluates each player's technological positioning, product architecture, geographic reach, and strategic emphasis on recycle-ready, mono-material, and high-barrier film systems. This competitive mapping enables clients to identify white-space opportunities, assess supplier consolidation risks, and anticipate pricing and capacity dynamics in their respective niches.
3. Recent Developments and Capability Investments
Market structure is not static; it is being actively rewritten by capital investments, technology launches, and process innovations. The report integrates a detailed chronology of recent developments that signal where the industry's capability frontier is expanding. Notable moves include Charter Next Generation's deployment of new 9-layer and 5-layer extrusion lines equipped with MDO technology to scale high-barrier, recycle-ready film output; Amcor's operational launch of a new MDO line in Peru to extend the global reach of its AmPrima Plus recycle-ready portfolio; Reifenhäuser's presentation of MDO Ultra Stretch technology at K 2025, showcasing an ultra-thin, process-stable all-PE MDO film architecture with EVOH barrier for mono-material packaging; and Constantia Flexibles' multi-million-euro investment in a 5-layer blown film line with inline MDO to advance PE-based mono-material structures. These developments are cataloged with source attribution and strategic interpretation, allowing readers to trace the cadence of investment and infer where competitive advantages are being built.
Worldwide Machine-Direction Orientation Films Market
4. Market Dynamics, Regulatory Catalysts, and Input Cost Pressures
No strategic assessment is complete without a rigorous examination of the forces that will amplify or constrain growth. The study embeds a dynamic analysis of the regulatory environment, raw material economics, and compliance requirements that shape procurement and conversion decisions. On the regulatory front, the tightening trajectory of the European Packaging and Packaging Waste Regulation (PPWR) is accelerating the adoption of MDO technology as a pathway to mono-material recyclability, with compliance expectations intensifying from 2030 onward. Concurrently, food-contact safety remains a non-negotiable constraint, with MDO-PE films for food packaging required to align with U.S. FDA 21 CFR standards and equivalent global material safety regulations.
On the input side, the report contextualizes the volatility and directionality of key feedstocks. Polypropylene, a critical resin for many MDO film grades, has experienced price movements tied to contract settlements, plant turnarounds, and regional supply disruptions. Price dynamics in North America and Northeast Asia are tracked alongside far-east Asian spot indicators, providing a nuanced view of cost pressures that converters and resin suppliers must factor into pricing strategy and margin management. These dynamics are not presented in isolation; they are woven into a broader narrative that explains how raw material trajectories, regulatory calendars, and consumer-brand sustainability commitments interact to define the operating environment for MDO film producers and converters.
The Competitive Arena: Who Shapes the MDO Films Market
The MDO films market is characterized by a moderately concentrated competitive structure, with the top three participants accounting for approximately 18.45 percent of collective revenue and the top five representing roughly 27.6 percent. This fragmentation beyond the leading tier indicates a market where regional specialization, application-specific expertise, and technology differentiation play decisive roles. The study's competitive analysis goes beyond market share arithmetic to evaluate the strategic postures of the key companies that define the market's technological and commercial contours.
In North America, Charter Next Generation has positioned itself as a technology-forward producer of high-barrier, recycle-ready MDO-PE films, exemplified by its GreenArrow portfolio and its investments in advanced multi-layer MDO lines that support matte-finish print substrates and mono-material packaging architectures. Trico Specialty Films complements this regional landscape with its monoaxially-oriented MOPP and MOPE offerings, including the ENVIRITE line tailored for mono-material packaging needs. Avery Dennison contributes to the competitive fabric with high-clarity MDO films serving label and flexible packaging applications, leveraging brand recognition and conversion expertise to embed its products within broader packaging ecosystems.
Europe hosts a dense cluster of capable producers and material innovators. RKW Group manufactures MDO films, barrier films, and complementary solutions with a focus on flexible packaging applications, while Polifilm Extrusion offers POLIPURE MDO PE films—available with or without EVOH barrier—that serve as printing substrates and mono-material packaging components designed to replace conventional PET, OPP, and OPA structures. NOWOFOL provides NOWOSTRAIGHT MDO films engineered for flexible stand-up and retort pouches in food packaging, and Lenzing Plastics extends its portfolio into industrial and packaging applications with LDO film solutions. Coveris, headquartered in Vienna, develops MDO films that balance sustainability credentials with high-performance flexible packaging requirements, while Borealis acts as a critical upstream enabler by supplying resins and technical support that underpin recyclable mono-material film production. Constantia Flexibles' recent investment in inline MDO technology further illustrates how the European value chain is integrating orientation capabilities to deliver PE-based mono-material structures such as EcoLamHighplus.
In Asia, the competitive landscape reflects both scale and rapid capability accumulation. Longdapac produces high-barrier MDO-PE films for recyclable flat-bottom and stand-up pouches, addressing the demands of modern retail and e-commerce packaging formats. Cloud Film and Jiangsu Qianrun New Material Technology round out the regional profile by supplying MDO PE films within broader oriented film portfolios that also encompass BOPP, BOPET, and related substrates. Amcor's global footprint, including its recent Peru-based MDO line expansion for AmPrima Plus recycle-ready films, demonstrates how multinational packaging leaders are extending MDO capabilities across Latin America and other growth markets to serve brand-owner sustainability commitments at scale. Additional participants such as Futamura, Toray Industries, and Polysack Plastic Industries contribute specialized MDO film solutions that span sustainable packaging, high-performance applications, and flexible packaging formats, reinforcing the depth and diversity of the global competitive set.
The strategic implication for clients is clear: competitive advantage in this market is increasingly derived from the ability to deliver mono-material, recycle-ready, high-barrier film systems with consistent processability and compliance assurance. Suppliers and converters that align their capabilities with these priorities—and that can navigate regional regulatory requirements and input cost volatility—are best positioned to capture share in a market that rewards technological integration and sustainability performance.
Market Dynamics: The Forces Reshaping 2026 and Beyond
The MDO films market does not evolve in a vacuum. Its trajectory is being shaped by an interlocking set of regulatory, economic, and technological forces that demand proactive strategic management. Three dynamics stand out as particularly consequential for 2026 decision-making.
Regulatory pressure as a technology accelerant. The global movement toward packaging recyclability is no longer a directional preference—it is becoming a compliance requirement. Stricter EU PPWR requirements on packaging recyclability, effective from 2030, are driving material substitution toward mono-material structures that can be efficiently recycled within existing streams. MDO technology is central to this transition because it enables polyethylene-based and polypropylene-based films to achieve the barrier performance, strength, and sealability required for demanding applications while preserving recyclability. In this context, MDO films are transitioning from a performance upgrade to a regulatory compliance pathway, which elevates their strategic importance for packaging portfolios targeting European and increasingly global markets.
Input cost volatility and margin resilience. The economics of MDO film production are sensitive to resin pricing, particularly for polypropylene and polyethylene grades that serve as primary feedstocks. Recent price movements—including increases tied to polymer-grade propylene contract settlements, plant turnarounds, and Middle East supply disruptions—illustrate the exposure that converters and resin suppliers face to commodity cycles and regional supply shocks. With polypropylene spot prices in far-east Asian markets experiencing notable upward movement and North American prices reacting to contract dynamics, margin management has become a central operational challenge. The study contextualizes these movements within a broader framework, helping clients anticipate cost trajectories, evaluate contract structures, and assess how input cost fluctuations may influence pricing power and competitive positioning across segments.
Compliance complexity as a market barrier and differentiator. Food-contact compliance and material safety are non-negotiable requirements that shape both product development and market access. MDO-PE films destined for food packaging must satisfy U.S. FDA 21 CFR standards and analogous global regulations, creating a compliance layer that raises the barrier to entry for undifferentiated producers while rewarding those with established quality systems and regulatory expertise. This dynamic reinforces the value of scale, technical capability, and compliance assurance in the competitive hierarchy, and it underscores why the study's analysis of regulatory requirements is integrated directly into its market dynamics assessment rather than treated as a peripheral footnote.
Why This Study Matters for 2026 Decision-Making
Enterprise strategies for 2026 cannot be built on generalized market narratives or lagging indicators. They require forward-looking, segment-aware intelligence that connects market sizing to the operational and competitive realities that drive value creation. This study is designed to meet that requirement. It provides a rigorously quantified baseline of market size and growth, a detailed segmentation map that reveals where growth and margin are concentrated, a competitive profiling framework that clarifies capability leadership and strategic positioning, and a dynamics assessment that anticipates the regulatory and economic forces most likely to alter the operating environment.
For converters evaluating capacity investments, the study offers context on where demand is structurally expanding and which film architectures are gaining commercial traction. For resin producers and equipment suppliers, it clarifies the technology requirements and application pulls that will shape procurement and co-development priorities. For brand owners and packaging specifiers, it illuminates the trade-offs between material performance, recyclability, compliance, and total cost, enabling more informed sourcing and portfolio decisions. In each case, the study's value lies in its ability to translate market data into strategic implication—turning size, share, and growth figures into actionable intelligence that informs capital deployment, supplier selection, and market-entry timing.
Navigating the Intelligence: What the Full Report Unlocks
This article has outlined the strategic contours of the Worldwide Machine-Direction Orientation Films Market and the analytical scope of the accompanying study. It has demonstrated the growth momentum, the competitive diversity, and the dynamic forces that make this market a critical consideration for 2026 planning. Yet the full depth of the intelligence—precise segment sizing, regional and application-level breakdowns, competitive capability comparisons, detailed investment chronologies, and forward projections through 2032—is contained within the complete report. For executive teams, strategy functions, and commercial leaders who require the granularity needed to validate investment theses, calibrate supply strategies, and benchmark competitive positioning, the full study provides the comprehensive evidence base that high-stakes decisions demand.
The Worldwide Machine-Direction Orientation Films Market is entering a phase in which technological capability, regulatory alignment, and sustainability performance will increasingly determine competitive outcomes. Organizations that equip themselves with detailed, forward-looking intelligence will be better positioned to anticipate shifts, seize opportunities, and manage risks in a market that rewards precision and strategic foresight. The complete report delivers that intelligence in a structured, decision-ready format, and it is available for access through our research portal for teams seeking to translate market insight into executable strategy.
For detailed analysis of this topic, please visit the official page: Worldwide Machine-Direction Orientation Films Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Auto Mahjong Table Market Hits $1,152M in 2025, Projected 6.85% CAGR Through 2032
By pmarketresearch, 2026-09-17
The Strategic Imperative of the Worldwide Automatic Mahjor Table Market: 2026 Outlook and Beyond
The intersection of traditional entertainment heritage and advanced automation is reshaping the leisure equipment landscape at an unprecedented pace. As we navigate the post-pandemic recovery and the subsequent boom in experiential consumption, the worldwide automatic mahjong table market stands out as a compelling case study in niche industrialization. For enterprise decision-makers, investors, and supply chain strategists, understanding the trajectory of this market is no longer merely an academic exercise; it is a critical component of capital allocation and product roadmap planning for the 2026 fiscal year and beyond.
In this deep dive introduction to our latest market research, PW Consulting presents a comprehensive analysis of the sector. Our goal is to equip stakeholders with the foresight needed to navigate a market characterized by rapid technological iteration, shifting consumer demographics, and intensifying global competition. This article serves as a strategic prelude to our full report, offering high-level insights into the market's trajectory while underscoring the depth of intelligence available in our complete study.
Market Trajectory: Resilience and Steady Expansion
The automatic mahjong table industry has demonstrated remarkable resilience over the past half-decade. Drawing from our extensive data compilation spanning from 2020 through the forecast horizon of 2032, the market has evolved from a post-recovery normalization phase into a period of sustained growth. The global revenue base, which stood at approximately $840 million in 2020, has consistently expanded, crossing the $1 billion threshold by 2024 and reaching an estimated $1.15 billion in the base year of 2025.
This upward trajectory is not accidental. It is underpinned by a convergence of urbanization trends, rising disposable incomes in key demographic hubs, and a renewed cultural emphasis on social gaming and entertainment gatherings. For 2026, our projections indicate that the market will advance to a valuation of roughly $1.26 billion. This figure represents more than just a numerical milestone; it signals a market that has successfully institutionalized automated technology within the leisure sector. The growth momentum is expected to continue, driven by product innovation and expanding application scope, culminating in a forward-looking valuation that underscores the sector's long-term viability.
For executives, this macro-level stability provides a safe harbor for strategic investment. Unlike highly volatile consumer electronics categories, the automatic mahjong table market benefits from a loyal user base and recurring replacement cycles within commercial establishments. However, the key to capturing this growth lies in understanding the nuanced dynamics beneath the surface level of total market size.
Segmentation Dynamics and Product Architecture
The market is not a monolith. Our analysis dissects the industry across three critical dimensions: product type, application environment, and geographical distribution. Each segment tells a unique story about how technology is being adopted and where the highest value pools are forming.
Product Type Evolution
The product landscape is divided primarily among four-legged static tables, foldable tables, and ultra-thin silent designs. While static models have historically anchored the market with their robust construction and professional-grade performance, the foldable segment has emerged as a powerful growth engine. The demand for space-efficient solutions is particularly pronounced in urban residential environments and multi-purpose venues where room utilization is paramount. Recent iterations of foldable automatic mahjong tables have addressed past durability concerns through the introduction of reinforced carbon-fiber composite hinge mechanisms and precision locking systems, significantly enhancing consumer confidence. Meanwhile, ultra-thin and silent models cater to premium residential and hospitality settings where aesthetics and acoustic comfort are prioritized, often incorporating advanced motor systems that reduce noise and accelerate shuffling cycles to under sixty-five seconds.
Application Segmentation
The application divide between commercial clubs and hotels versus residential home use reflects a dual-engine growth structure. Commercial establishments continue to drive substantial volume, leveraging automatic tables to enhance operational efficiency and customer experience in high-traffic gaming environments. However, the residential segment is witnessing accelerated adoption as consumers invest in home entertainment upgrades. This shift is facilitated by falling effective costs, improved aesthetic designs that blend with modern home decor, and features tailored for domestic play styles. The interplay between these two application streams creates a balanced ecosystem where commercial R&D often trickles down to consumer-grade products, and residential demand pushes manufacturers toward greater design sophistication.
Regional Nuances
Geographically, the market exhibits distinct concentration patterns. The Asia Pacific region remains the dominant force, reflecting both the cultural roots of the game and the concentration of manufacturing capabilities. North America and Europe represent mature but growing markets, where demand is often driven by diaspora communities, specialty leisure venues, and luxury furniture integration. The rest of world segment, while smaller in absolute terms, offers emerging opportunities as global awareness of the game expands. Understanding these regional weights is essential for companies planning export strategies, localization efforts, and supply chain optimization.
Competitive Intelligence: Key Players and Strategic Positioning
The competitive landscape is a mix of established multinational manufacturers, region-focused specialists, and agile producers leveraging scale in manufacturing hubs. Our research profiles ten leading entities that collectively shape the market's direction, each bringing distinct value propositions and strategic strengths.
Matsuoka Mechatronics (China) Co., Ltd. (Treyo) has cemented its position as one of the largest full-automatic mahjong table manufacturers worldwide since its establishment in nineteen ninety-five. Headquartered in the Xiaoshan Economic and Technology Development District of Hangzhou, Treyo specializes in high-quality models renowned for stable performance and advanced shuffling systems. Its export footprint spans Europe, Southeast Asia, the USA, and Australia. In March two thousand twenty-five, Treyo was featured as a top global supplier, emphasizing its R&D centers, technical testing protocols, and international export capabilities. This recognition reinforces its status as a benchmark for production reliability and global reach.
Automatic Door Market
Taiyo Giken Co., Ltd. (AMOS) , based in Wakayama Prefecture, Japan, brings over fifty years of mahjong equipment expertise. The AMOS brand is synonymous with premium automatic tables, holding a top market share in commercial automatic units used by professional leagues. Its dual focus on commercial and home-use models underscores a versatile product strategy that balances professional-grade durability with consumer accessibility.
QX Mahjong , operating from Singapore, has positioned itself as a premium provider focused on regional and local markets. Its foldable models equipped with wheels and the Smart Tile Pro fourth-generation system highlight a commitment to durability, safety certifications, and features tailored for local play preferences. In April two thousand twenty-six, QX released and promoted its new Smart Tile Pro fourth-generation catalog, positioning it as the future of mahjong with advanced features. This launch exemplifies the trend toward smart-enabled, user-centric product iterations.
Vismara , an Italian luxury furniture maker, represents the high-end design pole of the market. Models such as the Posh Deluxe and Ming incorporate hidden mechanisms for automatic tile sorting, leather upholstery, and premium finishes. This approach appeals to consumers who view the mahjong table as both a functional gaming device and a statement piece of interior design.
In China's manufacturing ecosystem, several key players drive volume and innovation. Yuyao Benjia Leisure Products Factory is recognized for automatic shuffling, sorting, and dealing capabilities paired with sleek modern designs and durable construction. Jiangsu Danbom Mechanical & Electrical Co., Ltd. integrates advanced mechanical and electrical technologies, pushing the boundaries of automation reliability. Hangzhou Cheers Technology Co., Limited serves diverse domestic and international customer needs, while Guangzhou Dajiang Electronic Technology Co., Ltd. has expanded production capacity to offer reliable models in accessible price ranges for domestic and export markets. Xingpai stands out as a premium leader known for dual-motor shuffling systems, high-end materials like solid walnut, touchscreen displays, and strong ratings across residential and commercial segments. Recent activity in September two thousand twenty-five saw Xingpai and Guangzhou Dajiang actively launching new foldable models that generated significant buyer interest at major trade events. USA MJ Table (USAMJTABLE) , based in Ontario, California, caters specifically to the North American market with tables suitable for American, Chinese, and other styles, offering shipping and assembly options that streamline adoption.
Strategic Dynamics and Industry Catalysts
Beyond the company roster, several overarching dynamics are reshaping the market's risk and reward profile. First, the consumer habits landscape is being rewritten by urbanization in Asia Pacific and rising disposable incomes. This combination is driving demand for space-efficient foldable automatic mahjong tables, a segment that is growing faster than non-foldable models. Manufacturers have responded not merely by shrinking footprints, but by engineering solutions that maintain performance integrity through advanced materials and locking technologies.
Second, product innovation continues to raise the bar. Premium models increasingly incorporate high-grade solid wood, walnut, oak, and carbon-fiber finishes alongside advanced motors for reduced noise and faster shuffling. This material and performance elevation supports higher price points and differentiates offerings in a crowded marketplace. It also creates a tiered market structure where entry-level accessibility coexists with luxury premiums.
Third, regulation and certification are becoming strategic differentiators. Compliance with durability and safety standards is no longer optional; it is a prerequisite for commercial procurement and a trust signal for residential buyers. Manufacturers that proactively align with the highest industry standards gain a competitive edge in tendering processes and consumer perception.
These dynamics collectively point to a market that is maturing yet still rich with innovation opportunities. The challenge for incumbents and entrants alike is to balance cost efficiency with differentiation, to navigate regional preferences without fragmenting production scale, and to anticipate the next wave of consumer expectations around smart features and aesthetic integration.
Market Concentration and Structural Considerations
The competitive architecture is moderately concentrated, a structural feature that influences pricing dynamics, barrier to entry, and partnership strategies. The top three players command a significant share of the market, while the top five collectively hold a substantial portion. This concentration suggests that scale, brand reputation, and technological leadership confer meaningful advantages. However, the presence of numerous specialized manufacturers and regional players ensures that niche segments, custom orders, and localized service requirements remain viable avenues for growth. For buyers and investors, this structure implies a market where dominant players provide benchmark reliability and global supply chain consistency, while smaller, agile firms can capture specific value pools through tailored solutions and rapid responsiveness.
The Strategic Value of Deep Intelligence
While the macro trends and competitive overviews outlined here provide a robust foundation for strategic thinking, they are only the beginning. The real leverage for enterprise decision-makers lies in the granular intelligence, segmentation breakdowns, scenario modeling, and actionable recommendations contained within our full Worldwide Automatic Mahjong Table Market research.
Our complete study offers a multi-layered examination of the market, including detailed segmentation analysis, regional growth drivers, pricing dynamics, supply chain mapping, and a forward-looking forecast through the year twenty thirty-two. It equips procurement teams with vendor evaluation frameworks, helps product managers identify white-space opportunities, and enables investors to model growth scenarios under varying assumptions. The report also integrates qualitative insights from industry developments, product launches, and supplier rankings, translating them into strategic implications.
We have intentionally withheld the deepest granular breakdowns, sub-segment revenue figures, and precise regional splits from this preview. This approach reflects our commitment to delivering exclusive, high-value intelligence that merits direct engagement. The full report is designed to be a decision-support tool, not just a data repository. It transforms raw market signals into clear strategic pathways.
Looking Ahead: Navigating 2026 and the Coming Cycle
As the market moves from a two thousand twenty-six valuation of approximately $1.26 billion toward a projected trajectory that surpasses $1.8 billion by the early twenty-thirtyties, the window for strategic positioning is wide open but not infinite. Companies that invest early in product differentiation, regional market penetration, and quality certification will be best placed to capture disproportionate value. Conversely, those that rely solely on cost competition without upgrading technology or brand positioning risk being squeezed by both premium innovators and scale-driven manufacturers.
The next phase of growth will be defined by who can best harmonize speed and reliability, who can integrate smart features without compromising durability, and who can serve diverse application environments with tailored solutions. It will also be shaped by supply chain agility, particularly as material costs, logistics, and regional demand patterns continue to evolve. Stakeholders who have a comprehensive, data-backed view of these forces will be able to act with confidence rather than react under pressure.
Conclusion: From Insight to Action
The worldwide automatic mahjong table market is at a pivotal juncture. It combines steady macroeconomic tailwinds with a vibrant competitive landscape and accelerating product innovation. For leaders across manufacturing, distribution, hospitality, and investment, the opportunity is clear: build strategies on the basis of rigorous, forward-looking analysis rather than fragmented signals.
This article has provided a strategic preview of the market's direction, the key players shaping it, and the dynamics that will determine winners and laggards. To move from direction to precision, we invite you to access the full Worldwide Automatic Mahjong Table Market research. There, you will find the detailed segmentation intelligence, regional analysis, competitive benchmarking, and scenario planning tools needed to make informed, high-impact decisions for 2026 and the years ahead. The market is expanding; the question is not whether to pay attention, but how deeply you want to understand the forces driving its next chapter.
Worldwide Automatic Mahjong Table Market
For detailed analysis of this topic, please visit the official page: Worldwide Automatic Mahjong Table Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Astrophotography Tracker Market Hits $163.5M in 2025, 9.72% CAGR
By pmarketresearch, 2026-09-17
Unlocking the Celestial Market: Strategic Insights from the 2026 Worldwide Star Tracker for Astrophotography Report
The night sky is no longer solely the domain of professional observatories. A democratization of astrophotography has transformed stargazing into a sophisticated hobby and a distinct commercial sector. As we move through 2026, understanding the trajectory of the Worldwide Star Tracker for Astrophotography Market is critical for stakeholders looking to align their strategies with celestial trends. Our latest market research, the Worldwide Star Tracker for Astrophotography Market Study, offers a comprehensive roadmap for navigating this expanding universe.
This report serves as an essential intelligence tool for decision-makers. It is not merely a collection of numbers but a strategic narrative explaining how technological innovation, consumer behavior, and competitive dynamics are converging to drive growth. For businesses operating in or adjacent to this sector, the insights contained herein are vital for capital allocation, product development, and geographic expansion plans throughout the forecast period.
Market Trajectory and Magnitudes
The financial outlook for the star tracker sector presents a compelling case for investment and growth. Our analysis tracks revenue trends from a historical base year of 2025 extending into the forecast horizon through 2032. The market has demonstrated consistent resilience and expansion, evolving from a niche interest into a recognized component of the broader imaging technology landscape.
Historical data reflects a steady climb in revenue generation. Starting from a baseline in 2020, the market has seen progressive annual growth, culminating in significant valuations by 2025. This momentum is projected to accelerate as we move beyond the current year. The forecast period indicates a robust upward trajectory, with valuations expected to scale significantly by the end of the decade. This growth is underpinned by a Compound Annual Growth Rate (CAGR) that signals strong sustained demand over the long term.
Such macroeconomic indicators suggest that the barrier to entry for high-quality astrophotography is lowering while the perceived value of these tools is rising. The infusion of capital into this sector suggests that the market is moving past early adoption phases into a stage of broader commercialization. Stakeholders who recognize this inflection point can position themselves to capture value before the market reaches saturation.
Segmentation and Structural Opportunities
To truly leverage this market potential, one must understand the structural composition of the industry. Our research deconstructs the market across multiple dimensions, revealing where value is being generated and where inefficiencies might exist.
The product landscape is categorized by mechanical and technological distinctions. We examine the performance and demand dynamics of portable units compared to more robust mounting solutions. The demand for compact, travel-friendly equipment continues to shape design priorities, while specific niche segments cater to users requiring specialized payload capacities. Understanding the revenue contribution of each product type allows manufacturers to optimize their portfolio mix according to shifting consumer preferences.
Worldwide Star Tracker for Astrophotography Market
Geographically, the consumption of astrophotography equipment is distributed across key global regions. Our analysis highlights the varying maturity levels of these markets. Some regions demonstrate established dominance driven by hobbyist density and disposable income, while emerging regions show promise based on growing astronomical communities and digital connectivity. Strategic players must differentiate their go-to-market strategies based on these regional idiosyncrasies rather than applying a uniform global approach.
Applications further define the market segments. From wide-field nightscape photography to deep space imaging and educational research, each use case commands different technical specifications and price points. The report details how these applications drive demand for specific features, such as tracking precision, payload capacity, and integration with digital imaging systems. By isolating these application drivers, companies can tailor their marketing messages and technical roadmaps to the specific needs of their target user bases.
Competitive Landscape and Corporate Intelligence
The competitive environment in the star tracker market is characterized by a mix of established optics manufacturers and specialized innovators. Our report provides a granular analysis of key companies that define the current market structure. These entities compete on dimensions of precision, portability, software integration, and price.
Major players such as iOptron and Sky-Watcher continue to influence the market with dedicated series designed for wide-field and deep-sky imaging. Their products often set the standard for features like WiFi control and payload capacity. Meanwhile, companies like Benro and Move Shoot Move are pushing the boundaries of smartphone integration and ultra-compact design, catering to the mobile-first astrophotographer. The presence of specialized manufacturers like Fornax Mounts and Vixen indicates a sustained demand for high-precision, mechanical reliability without relying on traditional gear drives.
Other significant entities, including NyxTech and Omegon, offer alternative approaches ranging from DIY kits to compact motorized solutions, ensuring that the market remains accessible to varying budget levels. This diversity in product offerings creates a fragmented yet vibrant ecosystem. The report analyzes the strategic positioning of these firms, noting how they differentiate themselves in a crowded field.
Competitive concentration is a notable factor. The market exhibits a level of consolidation where a core group of firms commands a significant share of revenue. However, the remaining share is distributed among numerous regional and niche players, suggesting opportunities for disruption. The report includes a detailed assessment of market concentration metrics, allowing investors to gauge the risk of market dominance versus the potential for new entrants to gain traction.
Industry Dynamics and Technological Drivers
Beyond static segmentation, the market is influenced by dynamic forces that are reshaping the operational environment. One of the primary challenges in consumer astrophotography remains the setup complexity, specifically regarding polar alignment. Our analysis highlights how recent product developments are addressing this bottleneck. Manufacturers are increasingly integrating smartphone applications, laser pointers, and enhanced alignment scopes to reduce the technical barrier for users. This shift from manual precision to assisted automation is a key driver of adoption among casual users.
On the regulatory and standards front, consumer star trackers generally operate under standard electronics safety and electromagnetic compatibility guidelines. While specific industry standards for amateur mounts are not rigidly defined beyond manufacturer quality controls, the emphasis on reliability is growing. This is evident in the broader context of the industry, where certifications and quality management systems are becoming more prevalent, even among consumer-focused goods.
Recent corporate activities also signal shifts in the broader ecosystem. For instance, expansions in manufacturing capabilities and new product line launches within the satellite and space sector often have spillover effects or indicate technological cross-pollination that can eventually benefit consumer-grade tracking technology. These developments remind stakeholders that the supply chain and technological landscape are interconnected with the wider aerospace and electronics industries.
Standardization in control interfaces is another trend. The move towards app-based control reduces reliance on traditional hardware interfaces, aligning star trackers with the broader Internet of Things (IoT) trends in consumer electronics. This convergence suggests that future iterations of these devices will likely prioritize seamless digital integration, firmware updates, and ecosystem compatibility.
Strategic Implications for 2026 Decisions
For executives and analysts, the value of this report lies in its actionable intelligence. The data provided allows for scenario planning in several critical areas. First, product development teams can use the segmentation data to identify which form factors and technical features are gaining traction. If the data indicates a surge in demand for lightweight equatorial mounts over traditional portable trackers, R&D budgets can be reallocated accordingly.
Second, geographic strategy is clarified. Knowing which regions are driving growth helps sales and distribution teams prioritize logistics, marketing spend, and partnerships. Ignoring high-growth regions or over-investing in stagnant ones can be costly; this report provides the metrics needed to avoid such pitfalls.
Third, competitive positioning is sharpened. By understanding the market concentration and the specific strengths of key competitors, companies can identify white spaces. Whether it is through pricing strategy, feature differentiation, or supply chain resilience, the report outlines the battlefield upon which companies are competing.
Furthermore, the forecast period extends to 2032, offering a long-term view that is essential for capital-intensive decisions. Infrastructure investments, facility expansions, and long-term supply contracts require visibility beyond the current fiscal year. The projected growth rates and market size evolutions provide the necessary confidence to commit resources to long-term initiatives.
Conclusion and Access to Full Intelligence
The Worldwide Star Tracker for Astrophotography Market is at a dynamic juncture. The combination of technological maturation, growing consumer interest in astronomy, and evolving competitive strategies creates a complex environment that requires careful navigation. Our research provides the depth required to understand these layers.
Astronomical Telescope Market
This article has summarized the strategic context and high-level market dynamics to establish the value of the comprehensive study. However, the true power of this intelligence lies in the detailed data tables, specific revenue breakdowns, and granular competitive profiles contained in the full report. To make informed decisions in 2026 and beyond, stakeholders need access to the complete dataset.
We invite industry leaders, investors, and analysts to review the full Worldwide Star Tracker for Astrophotography Market Research. By accessing the full document, you will gain the specific insights needed to drive your strategy forward, ensuring you remain aligned with the trajectory of this growing market.
For detailed analysis of this topic, please visit the official page: Worldwide Star Tracker for Astrophotography Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hitch Lock Market to Hit $18.4 Million by 2032; 4.15% CAGR Forecast (2026-2032)
By pmarketresearch, 2026-09-17
The Hitch Lock Market in 2026: Strategic Intelligence for Towing Security & Revenue Growth
Executive Summary: Why Strategic Depth Matters Now
The global hitch lock market has matured into a highly engineered, security-driven segment where product differentiation, distribution reach, and regulatory alignment determine competitive advantage. As towing volumes stabilize, fleet operations scale, and aftermarket security expectations rise, 2026 represents a decisive year for manufacturers, aftermarket distributors, and mobility-focused enterprises. PW Consulting’s latest market research delivers a structured, decision-ready view of how this landscape is evolving and where value is being created.
This study is designed as a strategic preview. It demonstrates the analytical rigor behind our latest Hitch Lock Market report, highlights the operational and competitive dynamics shaping 2026, and shows exactly how procurement, product, and go-to-market teams can translate market intelligence into actionable decisions. Core segmentation figures, regional revenue splits, and company-level performance breakdowns are reserved for the full report, because precise allocation data should inform investment choices—not simply be summarized.
Market Trajectory: What the Numbers Reveal About the Next Cycle
Over the 2020–2025 historical window, the hitch lock market expanded from approximately $10.25 million to $13.85 million, reflecting steady demand growth supported by trailer usage, towing accessory adoption, and an increasing emphasis on equipment security. The forecast period from 2026 through 2032 extends this momentum, with the market projected to reach $18.4 million by 2032.
At the center of this trajectory is a forecasted compound annual growth rate of 4.15% across the 2026–2032 period. That rate signals more than linear expansion. It indicates a market where volume growth, product mix evolution, and security upgrades are working together, but also where competitive intensity and margin pressure are likely to increase. For decision-makers, the strategic question is no longer whether the market is growing. It is where growth is concentrating, which product architectures are capturing share, and how upstream cost volatility reshapes pricing and sourcing strategies.
The full report unpacks these dynamics with a detailed forecast model, scenario analysis, and time-phased growth breakdowns that connect historical performance to forward-looking demand drivers. The preview below shows the framework, not the final allocation tables.
Report Scope: Operational Intelligence Built for 2026 Planning
This research is structured to support practical business decisions rather than abstract market commentary. The complete study integrates market sizing, segmentation logic, competitive benchmarking, and demand-side context into a single decision framework. Key operational components include:
Hitch Lock Market
- Historical performance analysis covering 2020 through 2025, enabling year-over-year trend interpretation and baseline validation for forward planning
- A 2026–2032 forecast architecture that maps anticipated revenue progression, regime shifts, and growth inflection points across the market lifecycle
- A structured segmentation review examining product-type dynamics and application-side demand behavior without exposing the full allocation detail in this preview
- Regional demand context that frames where volume is concentrated and which geographic markets warrant separate channel or sourcing strategies
- Competitive profiling of leading manufacturers and security-focused brands, including positioning, product philosophy, and recent strategic moves
- Industry dynamics analysis covering raw material exposure, regulatory influence, distribution trends, and aftermarket security preferences
The report also includes actionable takeaways for product planning, inventory strategy, channel expansion, and competitive response. Rather than presenting isolated statistics, the study is organized to help leadership answer questions such as which product categories justify further engineering investment, how distribution footprint changes affect addressable demand, and where security differentiation can support price realization.
Demand Architecture: Application and Product-Type Dynamics
Hitch lock demand is shaped by two interconnected forces: the vehicles and trailers that require protection, and the mechanical designs that define fit, durability, and user experience. In application terms, the market reflects a clear dependence on tow vehicles and trailers, with both categories contributing materially to overall consumption. Their relative importance is not just a volume story; it also influences product standards, installation expectations, and the security credentials buyers demand.
On the product side, the market spans multiple hitch lock architectures, each serving different installation environments and end-user preferences. Bent pin, flush pin, and threaded pin solutions all occupy distinct positions in the value chain, balancing ease of use, corrosion resistance, tamper resistance, and compatibility with receiver systems. As a result, the product mix is not uniform across customers or channels. Instead, it reflects a broader trend in which buyers increasingly evaluate hitch locks as part of an integrated towing security solution rather than as replaceable commodity hardware.
The full report details how these product and application categories interact with pricing, channel mix, and regional demand patterns. Because those breakdowns are central to portfolio planning and sales targeting, they are presented in full within the licensed study rather than summarized here.
Geographic Context: Where Demand Is Concentrated and Why It Matters
Regional demand distribution plays a critical role in shaping production planning, inventory positioning, and channel strategy. North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa each present different towing ecosystems, aftermarket maturity levels, and security expectations. As a result, a single global growth narrative can obscure important local differences in product requirements, competitive intensity, and distribution efficiency.
The report uses regional context to help clients assess where scale advantages matter most, where localized product configurations are needed, and where channel partnerships may accelerate penetration. Since regional revenue allocation and market share distribution are key inputs for expansion planning, those specifics are reserved for the complete market model. This ensures that strategic conclusions are grounded in the full dataset rather than in partial approximations.
Trailer Hitch Market
Competitive Landscape: Scale, Security, and Strategic Differentiation
The hitch lock market is characterized by meaningful concentration at the top, with leading players competing on manufacturing integrity, security performance, distribution breadth, and brand trust. The study’s competitive concentration metrics indicate a market where a relatively small group of established manufacturers accounts for a substantial share of total revenue, while specialized security brands continue to compete through engineering-led design and targeted product innovation.
Several companies define the current competitive rhythm:
- Proven Industries focuses on American-made heavy-duty trailer coupler locks, hitch locks, and security solutions with grinder-proof designs and lifetime warranty coverage, emphasizing RV, horse, and utility trailer applications.
- AMPLock, operating from Drummondville, Canada, produces CNC-machined heavy-duty hitch locks, coupler locks, and trailer security products using ductile iron and stainless steel, supported by patented key control systems.
- Altor Locks, based in Sterling, Virginia, takes an engineering-led approach with patented power tool-resistant ICON series trailer coupler locks, gooseneck locks, and hitch security solutions aimed at high-value assets.
- CURT Manufacturing is recognized as a leading USA-made trailer hitch and towing accessory manufacturer, offering a broad line of hitch locks, coupler locks, and receiver locks across multiple towing applications.
- Master Lock provides a wide range of weather-resistant trailer coupler locks, hitch pin locks, and towing security products designed for universal fit across multiple coupler and receiver sizes.
- BOLT Lock advances one-key lock technology solutions, including hitch receiver locks and trailer coupler locks, with an emphasis on convenient keyed-alike towing security.
Recent company-level activity reinforces how dynamic this space has become. In April 2026, AMPLock expanded heavy-duty trailer lock distribution across the United States, introducing over 20 custom-fit configurations for hitch, coupler, and related applications. That move reflects a broader push toward fitment specificity and channel reach. In August 2025, Altor Locks expanded its ICON product line with a new Gooseneck Trailer Lock, debuting at the NATDA Trailer Show with shipments beginning in Fall 2025. This launch highlights the continuing importance of specialized towing configurations and tool-resistant security design.
The complete report places these developments within a broader competitive mapping framework, connecting product launches, distribution expansion, and brand positioning to market share dynamics and strategic implications. That level of detail is essential for benchmarking and competitive response planning, which is why the full competitive analysis is provided in the licensed publication.
Market Dynamics: Material Volatility, Regulation, and Security Expectations
Beyond product and competition, the hitch lock market is influenced by upstream cost conditions and regulatory context. Raw material price volatility remains a significant operational concern. Industry data from March 2026 indicates that steel and alloy price fluctuations affect production costs, with nearly 41% of manufacturers reporting challenges linked to material cost instability. For hitch lock producers, this creates tension between engineering durability, manufacturing efficiency, and price competitiveness. Sourcing strategy, inventory timing, and product-grade selection become increasingly important as a result.
On the regulatory side, cargo securement expectations continue to shape how towing hardware is specified and evaluated. FMCSA cargo securement rules reference manufacturing standards for tiedowns, including welded steel chain specifications associated with the National Association of Chain Manufacturers. While hitch locks operate in a closely related but distinct part of the towing security ecosystem, the broader regulatory environment still matters because it influences buyer expectations, specification practices, and the perceived credibility of robust metal-based security hardware.
These dynamics are not peripheral. They influence cost structures, product specifications, and the value proposition that manufacturers can communicate to downstream buyers. The full report integrates these factors into a market dynamics assessment that links input-cost exposure, regulatory awareness, and end-user security demand to strategic planning assumptions.
Strategic Takeaways for 2026 Decision-Making
For executives, product leaders, and commercial teams, the hitch lock market in 2026 is best approached as a security-conscious, engineering-sensitive, and distribution-dependent growth environment. Several strategic priorities emerge from the broader direction of the market:
- Portfolio decisions should account for product-type fit and application-specific demand rather than treating hitch locks as interchangeable aftermarket items
- Material cost volatility requires disciplined sourcing, forecasting, and product-grade planning to protect margins without compromising durability claims
- Distribution expansion and custom-fit configuration strategies can materially affect reach, especially in markets where compatibility and installation ease drive purchase decisions
- Security differentiation, including tool-resistant design and strong warranty or fitment messaging, continues to support brand positioning in a concentrated market
- Regional demand variation should inform channel allocation, inventory planning, and localized product strategy rather than a single global rollout assumption
These priorities are directional by design. The full report translates them into quantified market sizing, segmentation breakdowns, forecast detail, and competitive benchmarking that can be directly applied to planning cycles.
Why the Full Report Is the Next Strategic Step
This preview demonstrates the analytical approach behind PW Consulting’s Hitch Lock Market research, but it intentionally leaves out the segment-level allocations, regional revenue splits, and detailed company comparisons that make the study actionable. The complete report provides the supporting model, the segmentation logic, the forecast architecture, and the competitive intelligence necessary to turn high-level trends into executable strategy.
For organizations evaluating product investment, channel expansion, procurement strategy, or competitive positioning in the towing security space, the full study offers a structured foundation for 2026 decision-making and beyond. The market is moving at a measured but consistent pace, and the companies that succeed will be those that combine security credibility with disciplined commercial execution. PW Consulting’s complete Hitch Lock Market report is designed to help leadership make those choices with greater confidence.
For detailed analysis of this topic, please visit the official page: Hitch Lock Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Cancel for Any Reason Travel Insurance Market to Hit $2.04B by 2032 at 13.23% CAGR
By pmarketresearch, 2026-09-17
Worldwide Cancel for Any Reason Travel Insurance Market: Strategic Intelligence for 2026 Decision-Making
The global travel insurance landscape has entered a period of structural transformation, driven by heightened traveler sensitivity to uncertainty and the rapid commercialization of flexible coverage products. At the center of this shift is the Cancel for Any Reason (CFAR) Travel Insurance market, a niche segment that has evolved from a marginal rider into a strategic differentiator for insurers, aggregators, and travel service providers. Our newly released Worldwide Cancel for Any Reason Travel Insurance Market study maps the segment across a 2020-2025 historical baseline and a 2026-2032 forecast horizon, translating complex demand signals, distribution realignments, and competitive maneuvers into an executive-ready intelligence framework. For leadership teams navigating product positioning, channel partnerships, or capital allocation in 2026, this research offers a disciplined lens on where value is concentrating and how the segment is likely to mature.
The macroeconomic trajectory captured in the study underscores why CFAR has moved from a peripheral insurance feature to a core strategic consideration. The overall market reached an estimated valuation of USD 852.4 Million in 2025, reflecting a compound trajectory from USD 280.45 Million in 2020. Over the forecast period extending to 2032, the segment is projected to follow a CAGR of 13.23%, with revenue scaling toward a multi-billion-dollar threshold as traveler expectations for granularity and flexibility continue to reshape purchase behavior. The analytical architecture of the study captures this expansion through layered segmentation by region, distribution channel, and traveler type, while also examining market concentration indicators that reveal how competitive power is distributed across leading providers. Crucially, the research goes beyond top-line sizing. It dissects the operational mechanics of CFAR adoption, the structural constraints imposed by regulatory environments, and the strategic implications for insurers balancing underwriting discipline against the growing appetite for unparalleled cancellation flexibility.
Report Scope and Operational Content
A market study earns its stature not through headline figures but through its capacity to inform real-world decisions. This research is structured to serve product strategists, distribution leaders, and competitive intelligence teams who require more than surface-level sizing. The report integrates historical progression analysis with forward-looking scenario modeling, allowing readers to assess momentum vectors rather than static snapshots. Coverage includes a detailed segmentation review that isolates how CFAR demand behaves across geographic markets, how it flows through distinct commercial channels, and how it maps to traveler personas ranging from individual leisure buyers to corporate travel programs and group travel arrangements.
The study is built around actionable analytical modules designed to support planning cycles in 2026. These include baseline market estimation, growth-rate derivation, and segmentation-level performance mapping that identifies where volume and value are accumulating. It also examines the structural factors that shape adoption, such as purchase-timing sensitivity, reimbursement design, and the interaction between standard trip cancellation benefits and CFAR upgrades. By tracing these mechanics, the report provides a practical foundation for assessing product design choices, pricing architecture, and channel strategy without reducing the segment to a single aggregate number.
Travel Insurance Market
Equally important is the report’s treatment of market structure and competitive behavior. Rather than presenting a simple roster of participants, the analysis situates each major provider within the broader ecosystem, highlighting how reimbursement ratios, add-on design, waiting period configurations, and regional eligibility rules shape competitive positioning. This allows executives to evaluate not just who is active in the market, but how different players are attempting to convert flexibility into durable share. For teams assessing partnership opportunities, benchmarking exercises, or entry strategies, this framing provides the kind of comparative clarity that supports informed judgment rather than speculative positioning.
Macro Trajectory and Demand Signals
The strength of the CFAR market is best understood as a function of both structural demand and episodic volatility. Over the historical period, the segment expanded through a combination of broader travel insurance penetration and a measurable shift toward coverage that gives travelers a discretionary exit option. That momentum accelerated in early 2026, when interest in Cancel for Any Reason coverage rose sharply in response to geopolitical instability and operational uncertainty. Industry reporting from March 2026 noted a significant uptick in buyer attention, reinforcing the pattern that CFAR demand often intensifies when travelers perceive higher unpredictability in itineraries, booking conditions, or broader travel environments.
This dynamic creates a strategic paradox for insurers and distributors. CFAR is not merely a product feature; it is a behavioral hedge that travelers increasingly value when plan certainty declines. At the same time, its design introduces complexity around timing, eligibility, and reimbursement structure. Most plans require purchase within a limited window after the initial trip deposit, require that the policyholder insure 100% of nonrefundable trip costs, and generally mandate cancellation at least 48 hours before departure. Reimbursement levels typically range from 50% to 75% of prepaid nonrefundable trip costs, with select offerings offering higher reimbursement ceilings. These parameters make CFAR highly attractive to risk-aware travelers, but they also mean that product design, communication clarity, and distribution timing become decisive factors in conversion.
Industry data suggests that approximately 10% of travel insurance plans purchased include CFAR coverage, a figure that reflects both the segment’s specialized appeal and its still-niche status within the broader travel insurance purchase base. That proportion matters because it signals room for expansion while also indicating that CFAR remains sensitive to price perception, plan bundling, and traveler awareness. The study interprets this trajectory not as a simple growth story, but as a demand curve shaped by consumer preference for flexibility, the influence of external disruption, and the way distribution channels translate that preference into completed purchases.
Segmentation Architecture and Strategic Implications
One of the most valuable contributions of the research is its segmentation logic. CFAR performance cannot be understood in isolation; it is mediated by where travelers buy coverage, who they are, and how regional market conditions influence product acceptance. The study maps these dimensions to reveal where demand is concentrated and where commercial opportunity may be underleveraged.
From a regional perspective, the analysis examines how mature versus emerging markets differ in their appetite for flexibility-driven coverage. Mature markets tend to exhibit higher baseline insurance penetration and more developed consumer familiarity with ancillary travel protections, while other regions may show faster relative growth as travel activity expands and buyers become more intentional about cancellation risk. The report avoids oversimplified regional generalizations. Instead, it evaluates market structure in a way that helps strategists determine whether CFAR should be positioned as a premium differentiator, a conversion enhancer, or a bundled protection element depending on local demand characteristics.
Distribution channel analysis is equally critical. The way CFAR is sold shapes both visibility and trust. Direct online channels and insurtech platforms play an outsized role in making flexible coverage discoverable, while travel agencies and online travel agencies contribute volume through trip-linked purchase pathways. Traditional insurance brokers continue to serve segments where personalized advisory interaction influences product selection. The study evaluates how these channels differ in their ability to educate buyers on CFAR’s terms, manage purchase timing, and position reimbursement expectations. For operators, this analysis supports decisions about where to invest in consumer-facing explanation, where to optimize embedment into booking flows, and where broker-led guidance may create premiumization opportunities.
Traveler type segmentation further sharpens the strategic view. Individual and leisure travelers often drive discretionary CFAR purchases because they are more directly exposed to personal trip disruption risk. Business and corporate travelers represent a distinct value pool, where cancellation flexibility may intersect with policy administration, duty-of-care considerations, and travel program compliance. Group and family travelers introduce different purchasing dynamics, often balancing total trip cost coverage against the convenience of a shared policy. By separating these personas, the research enables more precise messaging, channel targeting, and product configuration decisions.
Competitive Landscape and Product Differentiation
CFAR is a segment where differentiation is often subtle but commercially decisive. The study profiles leading participants and evaluates how each uses reimbursement design, add-on structure, waiting periods, and eligibility rules to create competitive posture. Several U.S.-based providers anchor the market, and each illustrates a different approach to converting flexibility into perceived value.
Allianz Travel Insurance offers CFAR or a Cancel Anytime upgrade on select plans such as OneTrip Prime and OneTrip Premier, with reimbursement reaching up to 80% of prepaid nonrefundable trip costs and the ability to cancel as late as the day of departure under certain configurations. That positioning reflects a strategy centered on premium reimbursement ceilings and late-window flexibility. Seven Corners provides CFAR as an optional add-on on plans including Trip Protection Basic, with reimbursement up to 75% and a reputation for short waiting periods, which can be an important conversion factor for time-sensitive buyers. Travel Insured International includes optional CFAR benefits on its Worldwide Trip Protector plans, reimbursing up to 75% for cancellations not otherwise covered and emphasizing broad trip protection integration.
IMG offers CFAR as an optional add-on on iTravelInsured plans such as Travel LX, Travel SE, and Choice, with reimbursement up to 75%, though availability is not uniform across all states. Trawick International has pursued a distinct product-led strategy by embedding CFAR within its Safe Travels plan family, including the Safe Travels AnyReason plan, which provides 75% reimbursement without an additional fee. That design is notable because it reduces the friction typically associated with add-on pricing and reframes CFAR as an integrated plan attribute rather than a separate purchase decision. WorldTrips offers CFAR coverage on its Atlas Journey series, aiming to give travelers a path to recover nonrefundable trip costs for any reason, while Travelex Insurance Services incorporates CFAR options and positions them around value and emergency coverage breadth.
Travel Guard, part of AIG, offers an optional Cancel for Any Reason add-on that reimburses a percentage of nonrefundable trip costs, reflecting the scale and brand visibility that large travel insurance franchises bring to the segment. World Nomads provides an optional CFAR upgrade on Explorer and Epic plans for U.S. residents, with eligibility limitations in certain jurisdictions. Generali Global Assistance offers optional CFAR on Premium plans with reimbursement up to 75% of nonrefundable trip costs, aligning flexibility with higher-tier plan positioning. Tin Leg has been identified among competitive CFAR providers for 2026, suggesting ongoing entry and repositioning activity in the market. Faye is noted for CFAR coverage linked to non-medical evacuation benefits, illustrating how some providers associate flexible cancellation with broader protection narratives.
These profiles are not presented as isolated product summaries. They are used to interpret how reimbursement ceilings, fee structures, timing rules, and regional eligibility constraints influence competitive advantage. The report also tracks structural developments that alter market expectations, including product launches that reset baseline assumptions. For example, Trawick International’s 2024 launch of Safe Travels AnyReason introduced an industry-first plan with embedded CFAR offering 75% reimbursement without an additional fee, a move that signaled how product architecture could be used to lower purchase friction. More recently, industry attention to rising CFAR interest in early 2026 has reinforced the idea that demand for flexible cancellation is responsive to broader uncertainty cycles.
Regulatory and Structural Dynamics
Any credible CFAR strategy must contend with the regulatory and operational constraints that shape offerable terms. The study dedicates significant attention to the forces that determine what can be sold, how it can be presented, and where limitations apply. CFAR coverage is subject to time-sensitive purchase windows, requirements that 100% of nonrefundable trip costs be insured, and cancellation thresholds that commonly require action at least 48 hours before departure. These operational rules influence both consumer behavior and product design, making them essential considerations for anyone evaluating conversion pathways or underwriting exposure.
Regulatory nuance is equally important. In certain jurisdictions, CFAR benefits are treated with specific interpretive guidance rather than as standard insurance coverage. For instance, New York DFS Insurance Circular Letter No. 4 from 2020 clarified that CFAR benefits do not technically qualify as insurance in the traditional sense and provided guidelines for offering them as incidental benefits or within standalone contracts. As a result, CFAR may not be available under standard policy configurations in some environments, and in practical terms, certain providers do not offer CFAR to New York residents under specific plans. These state-level and jurisdictional distinctions create fragmented availability and can affect both market sizing and competitive reach.
From a market structure standpoint, the study also examines concentration indicators that reveal how consolidated the competitive base is. The research captures market concentration metrics including a CR3 of 38.45% and a CR5 of 52.3%, signaling that a limited group of leading participants accounts for a substantial share of the segment while still leaving meaningful space for specialty providers, insurtech entrants, and distribution-led differentiation. This concentration picture matters because it helps leaders gauge how crowded the core is, where differentiation is most needed, and whether share gains are likely to come from product innovation, channel leverage, or brand trust.
Strategic Takeaways for 2026 Decision-Making
For executives planning around 2026, the report’s central value lies in converting market momentum into decision-grade insight. The CFAR segment is expanding in a context where traveler demand for flexibility is no longer marginal, but it remains sensitive to purchase timing, reimbursement framing, and regulatory boundaries. That combination means the winners are unlikely to be determined solely by who offers CFAR, but by who can make it understandable, accessible, and commercially coherent within the purchase journey.
Several strategic implications emerge from the analysis. First, product design and communication clarity are becoming competitive levers in their own right. Because CFAR depends on narrow purchase windows and specific eligibility conditions, providers and distributors that can reduce confusion and align messaging with real traveler decision points may capture disproportionate conversion advantage. Second, channel strategy deserves deliberate attention. Online direct and insurtech pathways can strengthen visibility and speed to purchase, while agency and OTA touchpoints can reinforce trust and trip-linked relevance. The optimal mix depends on the target traveler type and the regional market being addressed.
Third, reimbursement architecture is not merely a marketing feature; it is a structural differentiator. Higher reimbursement ceilings, waived add-on fees, and short waiting periods each address different sources of buyer resistance. Providers that align these elements with their broader plan portfolio can shape perceived value in ways that extend beyond price competition. Fourth, regulatory heterogeneity must be managed carefully. Jurisdiction-specific availability and treatment of CFAR create both constraints and opportunities, especially for organizations operating across multiple states or planning multi-market expansion. Understanding where CFAR can be offered, how it can be presented, and which configurations are permissible is essential to avoiding compliance friction and identifying under-served pockets of demand.
Finally, the report is intended to help leadership teams look beyond cyclical spikes and assess the durability of demand. The recent rise in interest is consistent with the pattern that CFAR becomes more attractive when uncertainty increases, but the longer-term opportunity depends on whether flexible cancellation can be normalized as an expected element of travel protection rather than a crisis-driven purchase. The study provides the context to evaluate that transition, including how market concentration, distribution dynamics, and product innovation interact to determine whether CFAR remains a premium add-on or becomes a more widely embedded purchase expectation.
Worldwide Cancel for Any Reason Travel Insurance Market
Why This Research Matters Now
Market intelligence is most valuable when it enables decisions that are both timely and precise. The Worldwide Cancel for Any Reason Travel Insurance Market study is designed to support that standard by combining historical context, forward-looking growth modeling, segmentation analysis, and competitive profiling in a single analytical framework. It gives decision-makers a structured view of how the segment has evolved, how it is currently contested, and where strategic attention is likely to produce the greatest return in 2026 and beyond.
At the same time, the study intentionally preserves depth that cannot be fully captured in a summary format. Segmentation-level performance, regional market behavior, channel-specific flow patterns, and the full competitive comparison across providers are developed in detail within the complete report. These components are essential for teams that need to benchmark against specific peers, evaluate channel investments, or build product strategies with a clear view of where value is concentrating. The overview presented here is intended to establish the strategic contours and demonstrate the research’s analytical rigor, while inviting a deeper engagement with the full dataset and interpretive commentary.
For organizations seeking to act on the CFAR opportunity with discipline rather than speculation, this research provides the foundation. It clarifies the market’s growth logic, identifies the forces shaping demand, and frames the competitive and regulatory realities that will influence execution. The complete report extends that foundation into the level of detail required for operational planning, making it a strategic reference for executives, product leaders, and market analysts who need to navigate a segment that is expanding quickly, differentiating sharply, and becoming increasingly central to the future of travel insurance.
For detailed analysis of this topic, please visit the official page: Worldwide Cancel for Any Reason Travel Insurance Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Flow Field Plate Market to Hit $15.9B by 2032, 28.45% CAGR
By pmarketresearch, 2026-09-17
Beyond the Hydrogen Horizon: Strategic Intelligence in the Global Flow Field Plate Market through 2032
The global energy transition has entered a phase of decisive industrial scaling. Nowhere is this trajectory more evident than in the flow field plate sector, a critical subsystem governing fluid distribution, electrical conductivity, and mechanical durability across fuel cell stacks, electrolyzers, and stationary power installations. As capital allocation shifts from laboratory validation to gigawatt-scale manufacturing, decision-makers require more than directional trends. They need granular, forward-looking intelligence that maps technology roadmaps, supply chain inflection points, and competitive positioning against a rapidly compressing investment window. Our newly released Worldwide Flow Field Plate Market research delivers precisely that. Built on a rigorous methodology spanning historical tracking from 2020 through the base year of 2025, and projecting forward across a 2026 to 2032 forecast horizon, this study equips executives, procurement leaders, and strategic planners with the analytical leverage required to navigate a market undergoing structural acceleration.
In 2026, the operational landscape for hydrogen technologies and electrochemical power systems is no longer defined by theoretical potential. It is defined by cost curves, manufacturing throughput, and supply chain resilience. The flow field plate has evolved from a passive component into a performance bottleneck and a differentiation lever. Material selection, surface engineering, coating architectures, and production tolerances directly dictate stack longevity, power density, and levelized cost of energy. Companies that treat this segment as a commodity procurement category are rapidly ceding ground to competitors who recognize it as a strategic capability node. Our research is structured to close that awareness gap, translating macroeconomic momentum into actionable market architecture.
The Macro Trajectory: Decoding the Growth Inflection
The market's historical trajectory tells a story of compounding adoption. Over the past half-decade, revenue generation has escalated from a foundational baseline in 2020 to a substantially expanded operational footprint by 2025. That momentum does not plateau; it compounds. Our forecast model projects the global market to surpass the mid-three-billion-dollar threshold in 2026, followed by sustained expansion that pushes total industry revenue well beyond the fifteen-billion-dollar mark by the close of the 2032 projection window. At the core of this expansion sits a compound annual growth rate of 28.45 percent, a figure that reflects not merely cyclical demand but a structural realignment in how clean energy infrastructure is manufactured, deployed, and scaled.
Such growth is not distributed uniformly across time, geography, or application. It concentrates in segments where performance requirements intersect with manufacturing readiness, regulatory tailwinds, and capital deployment velocity. For strategic planners, the implication is clear: headline figures are useful for boardroom context, but segment-level dynamics dictate where capacity should be allocated, where supplier partnerships should be forged, and where technical roadmaps should be prioritized. Our report dissects these dynamics without reducing them to static snapshots, instead presenting them as interdependent variables that shift as technology maturation curves cross commercial adoption thresholds.
The strategic value of this market intelligence lies in its ability to separate signal from noise. Raw material constraints, coating specifications, throughput limitations, and regional trade policy adjustments all exert measurable pressure on cost structures and delivery timelines. By mapping these pressures against demand trajectories, the study enables organizations to anticipate supply-demand mismatches before they become operational liabilities. Executives can evaluate whether to lock in long-term feedstock agreements, diversify supplier bases, or invest in proprietary forming and etching capabilities. The data does not prescribe a single path; it illuminates the trade-offs embedded in each strategic choice.
What the Report Delivers: Operational Intelligence, Not Just Forecasts
A market study earns its place on an executive dashboard only when it translates into operational decision-making. Our Worldwide Flow Field Plate Market research is engineered around that standard. The publication moves systematically through the architecture of the industry, beginning with a comprehensive segmentation framework that isolates material type, application domain, and regional deployment patterns. Rather than presenting these splits as isolated tables, the analysis contextualizes them within technology adoption lifecycles, manufacturing scalability constraints, and end-use performance requirements.
The material segment analysis examines how metallic, graphite, and composite flow field plates compete across different performance and cost envelopes. Each category carries distinct implications for conductivity, corrosion resistance, manufacturing complexity, and supply chain dependencies. The application analysis traces how demand differentiates across fuel cell electric vehicles, stationary power generation, and electrolyzer deployments, highlighting where volume scaling, durability thresholds, and integration requirements diverge. Regional analysis maps where manufacturing capacity, end-market demand, and policy support converge, enabling readers to assess localization strategies, tariff exposure, and logistics optimization opportunities without relying on superficial geographic generalizations.
Beyond segmentation, the report delivers a deep operational review of production methodologies and technology roadmaps. Photochemical etching, progressive die forming, compression molding, high-velocity forming, and advanced coating architectures are evaluated against throughput, precision, capital intensity, and scalability. This technical grounding matters because manufacturing process selection directly influences unit economics, quality consistency, and the ability to meet emerging performance targets set by government research programs and industry consortia. Decision-makers gain a structured basis for evaluating whether to outsource, co-develop, or internalize critical production capabilities.
The study also integrates competitive benchmarking, supplier capability mapping, and recent market movements that signal shifting industry momentum. New product introductions, capacity expansions, strategic partnerships, and technology demonstrations are analyzed not as isolated headlines but as indicators of where capital and engineering effort are being concentrated. By connecting these developments to broader supply chain and regulatory dynamics, the report provides a living map of competitive positioning that remains relevant as the market matures.
Competitive Architecture: Navigating a Fragmented but Consolidating Field
The flow field plate ecosystem is characterized by a blend of specialized manufacturers, integrated fuel cell developers, and industrial players expanding into hydrogen-adjacent production. Market concentration metrics indicate that the top three players account for 38.4 percent of industry revenue, while the top five collectively capture 52.65 percent. This concentration profile signals a market that is broad enough to accommodate diverse entrants yet structured enough that scale, process know-how, and customer integration relationships confer meaningful defensive advantages.
Worldwide Bipolar Plate Fuel Cell Market
Players such as Switzer and Precision Micro have built reputations around photochemical machining and chemical etching, offering high-precision metallic bipolar and flow field plates that serve electrolyzer, hydrogen generation, and fuel cell applications across prototyping and high-volume production. Their capabilities emphasize design flexibility and tight geometric control, attributes that matter when flow distribution and pressure drop management directly influence stack efficiency. Fuel Cell Store and Ensinger address the graphite segment with customizable plate designs and scalable production pathways, supporting electrochemical devices that prioritize different trade-offs between weight, conductivity, and corrosion behavior. In China, TMNetch focuses on photochemical etching for metallic plates, emphasizing durability and energy efficiency in fuel cell environments, while Interplex leverages corrosion-resistant stainless steel formulations with PVD coatings to extend operational lifespan in demanding PEM applications.
On the industrial scaling frontier, companies like Dana Incorporated and EKPO Fuel Cell Technologies bring high-speed forming, conductive coatings, and integrated sealing architectures to metallic bipolar plate production, aligning their output with high-volume PEM fuel cell and electrolyzer requirements. Dana's recent product introduction for high-density electrolyzers, which pairs titanium or steel substrates with advanced forming, conductive coating, and molded elastomer sealing, illustrates how incremental engineering refinements target both power density and cost reduction simultaneously. Schunk Group contributes compression-molded graphite bipolar plates with integrated flow fields, offering single-plate and redox flow cell solutions that support energy storage and fuel cell architectures. Ballard Power Systems continues to advance flexible graphite bipolar plate lines and next-generation manufacturing capacity, supported by policy-aligned funding initiatives that underscore the strategic importance of domestic production readiness.
Worldwide Flow Field Plate Market
The competitive landscape also includes operators scaling proprietary manufacturing technologies. Cell Impact's high-velocity forming approach and large-scale production facilities position it to serve fuel cell and electrolyzer demand at volume, reinforced by partnerships that combine forming with welding technology for high-volume bipolar flow plate production. SITEC and Precision Resource extend the field further by covering coil-to-installation manufacturing pathways and specialized metal forming for zero-emission vehicles and green hydrogen production. Taken together, these players illustrate a market where competitive advantage is increasingly defined by process engineering, coating expertise, integration support, and the ability to move from prototype validation to reliable series production.
Market Dynamics and the Forces Reshaping Supply and Demand
No forward-looking strategy is complete without a clear understanding of the forces that can accelerate, delay, or redirect market growth. Raw material considerations remain foundational. Graphite-based flow field plates depend on high-purity feedstock, while composite variants typically carry substantial graphite loading combined with polymer binders, creating a material architecture that balances conductivity with mechanical and chemical resilience. Metallic plates, by contrast, commonly rely on stainless steel or titanium substrates, with precision steel strip in narrow thickness ranges enabling complex flow field forming. These material realities link the flow field plate market directly to upstream commodity dynamics, specialty coating availability, and precision metallurgy supply chains.
Regulatory and policy frameworks exert equally directional influence. Support for bipolar plate manufacturing advancement continues through government-backed programs that fund next-generation production lines and technology development initiatives. Technical targets for PEM fuel cell bipolar plates increasingly emphasize electrical conductivity, areal specific resistance, and cost-per-kilowatt thresholds at volume. These targets are not abstract benchmarks; they function as design constraints that shape R&D priorities, supplier qualification criteria, and procurement negotiations. Organizations that internalize these performance and cost targets early can align their engineering roadmaps with the standards that will govern future market access.
Trade policy and regional cost dynamics add another layer of strategic complexity. Tariff adjustments affecting metallic feedstocks and specialty coatings have already altered unit input costs for manufacturers operating in affected markets. Such shifts influence supplier selection, regional sourcing strategies, and the economic calculus behind domestic versus imported production. Meanwhile, recent capacity expansions and technology demonstrations signal where the industry is placing its bets. Large-scale production line construction for flow plate and vanadium flow battery-related applications, modular pilot plants for rapid and cost-effective bipolar plate production, and partnership agreements targeting high-volume manufacturing installation all point to an ecosystem moving from fragmented experimentation toward coordinated commercial scaling.
For corporate strategy teams, these dynamics create both risk and optionality. Supply chain diversification, long-term coating and feedstock agreements, localization of critical process steps, and selective vertical integration all become viable responses depending on an organization's risk tolerance, capital position, and customer commitments. The report's value lies in helping leaders evaluate those responses against a structured map of market forces rather than reacting to isolated events after the fact.
Why 2026 Is the Strategic Inflection Point
2026 represents more than another forecast year. It marks the point at which early adoption momentum transitions into industrial scaling, where procurement decisions begin to lock in capabilities for the remainder of the decade, and where competitive positioning becomes increasingly difficult to reverse. The flow field plate market is expanding at a pace that rewards organizations with clear technology roadmaps, disciplined supplier strategies, and a realistic understanding of where manufacturing complexity can be absorbed internally versus where it should be managed through partnerships.
The research does not merely project growth; it structures the decision environment around the variables that actually determine outcomes. Which material class aligns with your performance requirements and cost targets? Where does your application mix concentrate, and how does that shape volume commitments? Which manufacturing processes offer the best path to precision, throughput, and scalability for your specific product architecture? How do recent product launches, capacity expansions, and partnership announcements change the competitive baseline you are operating against? These are the questions our study is designed to answer with analytical rigor rather than directional intuition.
Executives who engage with this intelligence early gain a measurable advantage in opportunity prioritization, risk mitigation, and capital deployment timing. They can distinguish between temporary demand spikes and durable structural growth, between capability claims and proven production readiness, and between regional opportunities that justify localization investment and those that remain better served through established supply channels. In a market moving at a 28.45 percent compound annual growth rate toward a 2032 revenue trajectory that redefines the scale of hydrogen and electrochemical infrastructure, strategic latency carries real cost.
Closing the Intelligence Gap: Access the Full Study
The macro trajectory, segmentation architecture, competitive mappings, and dynamic force analyses summarized here provide a substantive preview of the strategic landscape. They establish the analytical foundation and demonstrate the depth of methodology embedded in the full publication. Yet the most consequential details, the segment-level dimensions, the regional deployment patterns, the application-specific volume dynamics, and the supplier-level capability comparisons that inform precise go-to-market and procurement decisions, are intentionally held within the complete report.
This is not a limitation of the preview; it is the design of a strategic intelligence product. Executive briefings establish context and credibility. Detailed market data, scenario-ready segmentation, and granular competitive assessments enable execution. Organizations that require precise figures for capacity planning, supplier negotiation, technology investment justification, and market entry evaluation will find the complete Worldwide Flow Field Plate Market research built for exactly that purpose. The full study translates directional confidence into operational precision, giving strategic teams the evidence base required to commit capital, align engineering roadmaps, and position competitively across the 2026 to 2032 horizon.
Access the complete market research to secure the full segmentation data, regional deployment intelligence, application-level demand analysis, and competitive benchmarking required to move from strategic awareness to decisive action. In a market scaling this rapidly, the difference between informed positioning and reactive adaptation is access to the right intelligence at the right time.
For detailed analysis of this topic, please visit the official page: Worldwide Flow Field Plate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com